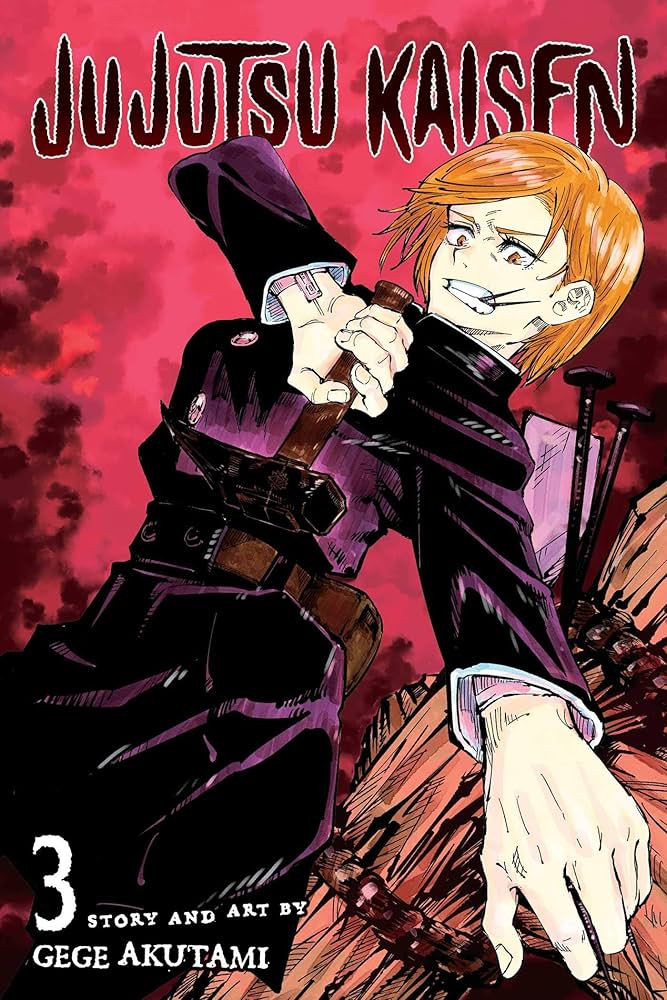
Jujutsu Kaisen, Vol. 3 (Volume 3) Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.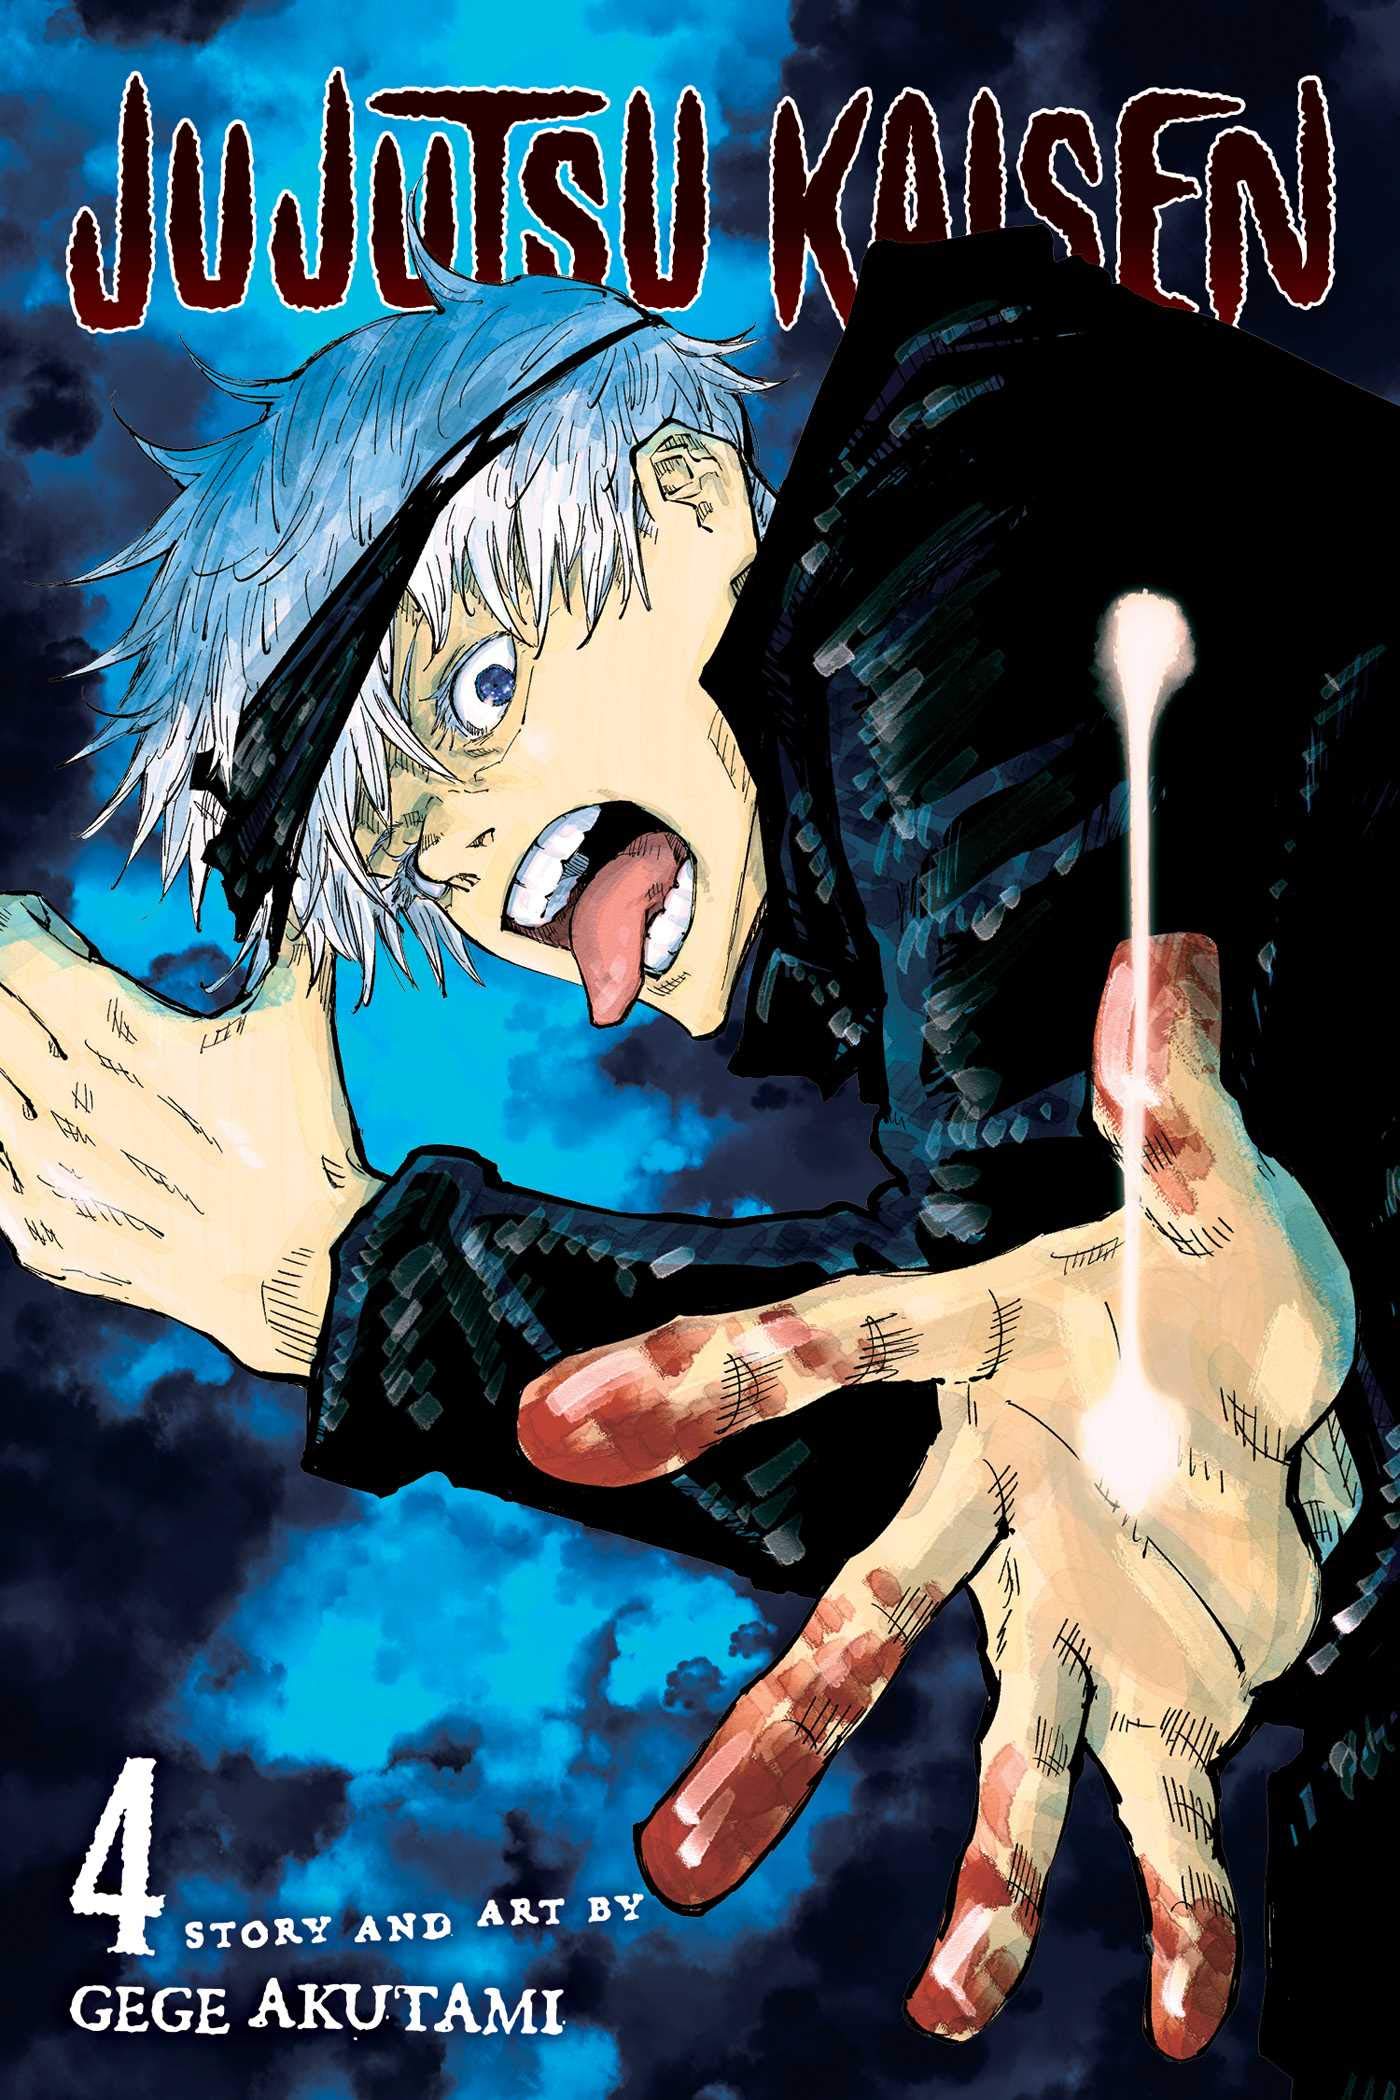
Jujutsu Kaisen, Vol. 04: Volume 4 Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.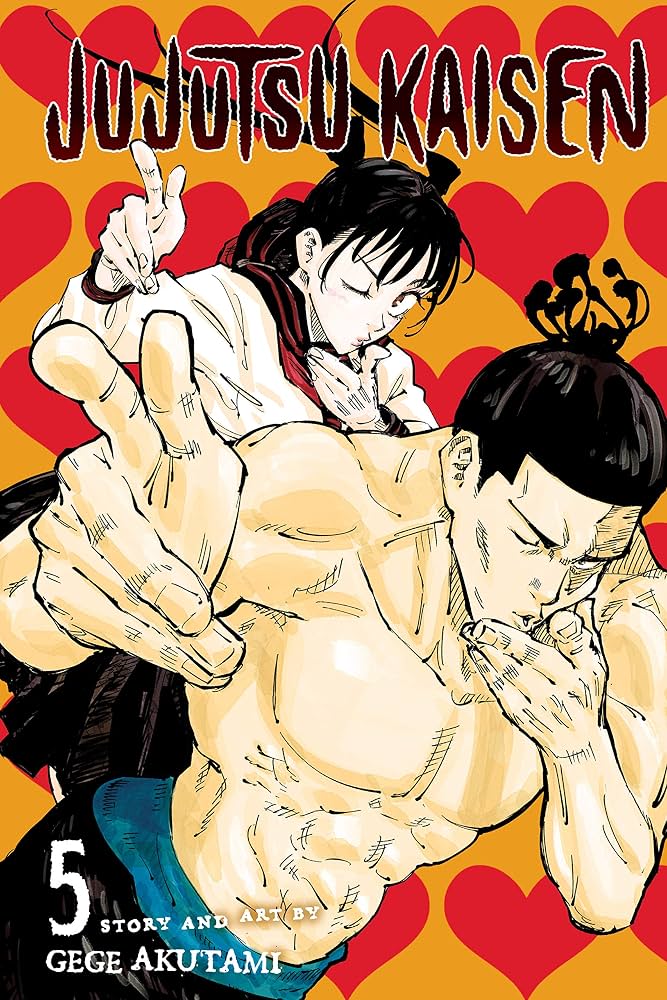
Jujutsu Kaisen, Vol. 5: Volume 5 Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.
Jujutsu Kaisen, Vol. 02 Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.
Jujutsu Kaisen, Vol. 1: Volume 1
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.
The 7 Habits of Highly Effective People Paperback
Original price was: ₹499.00.₹249.00Current price is: ₹249.00.
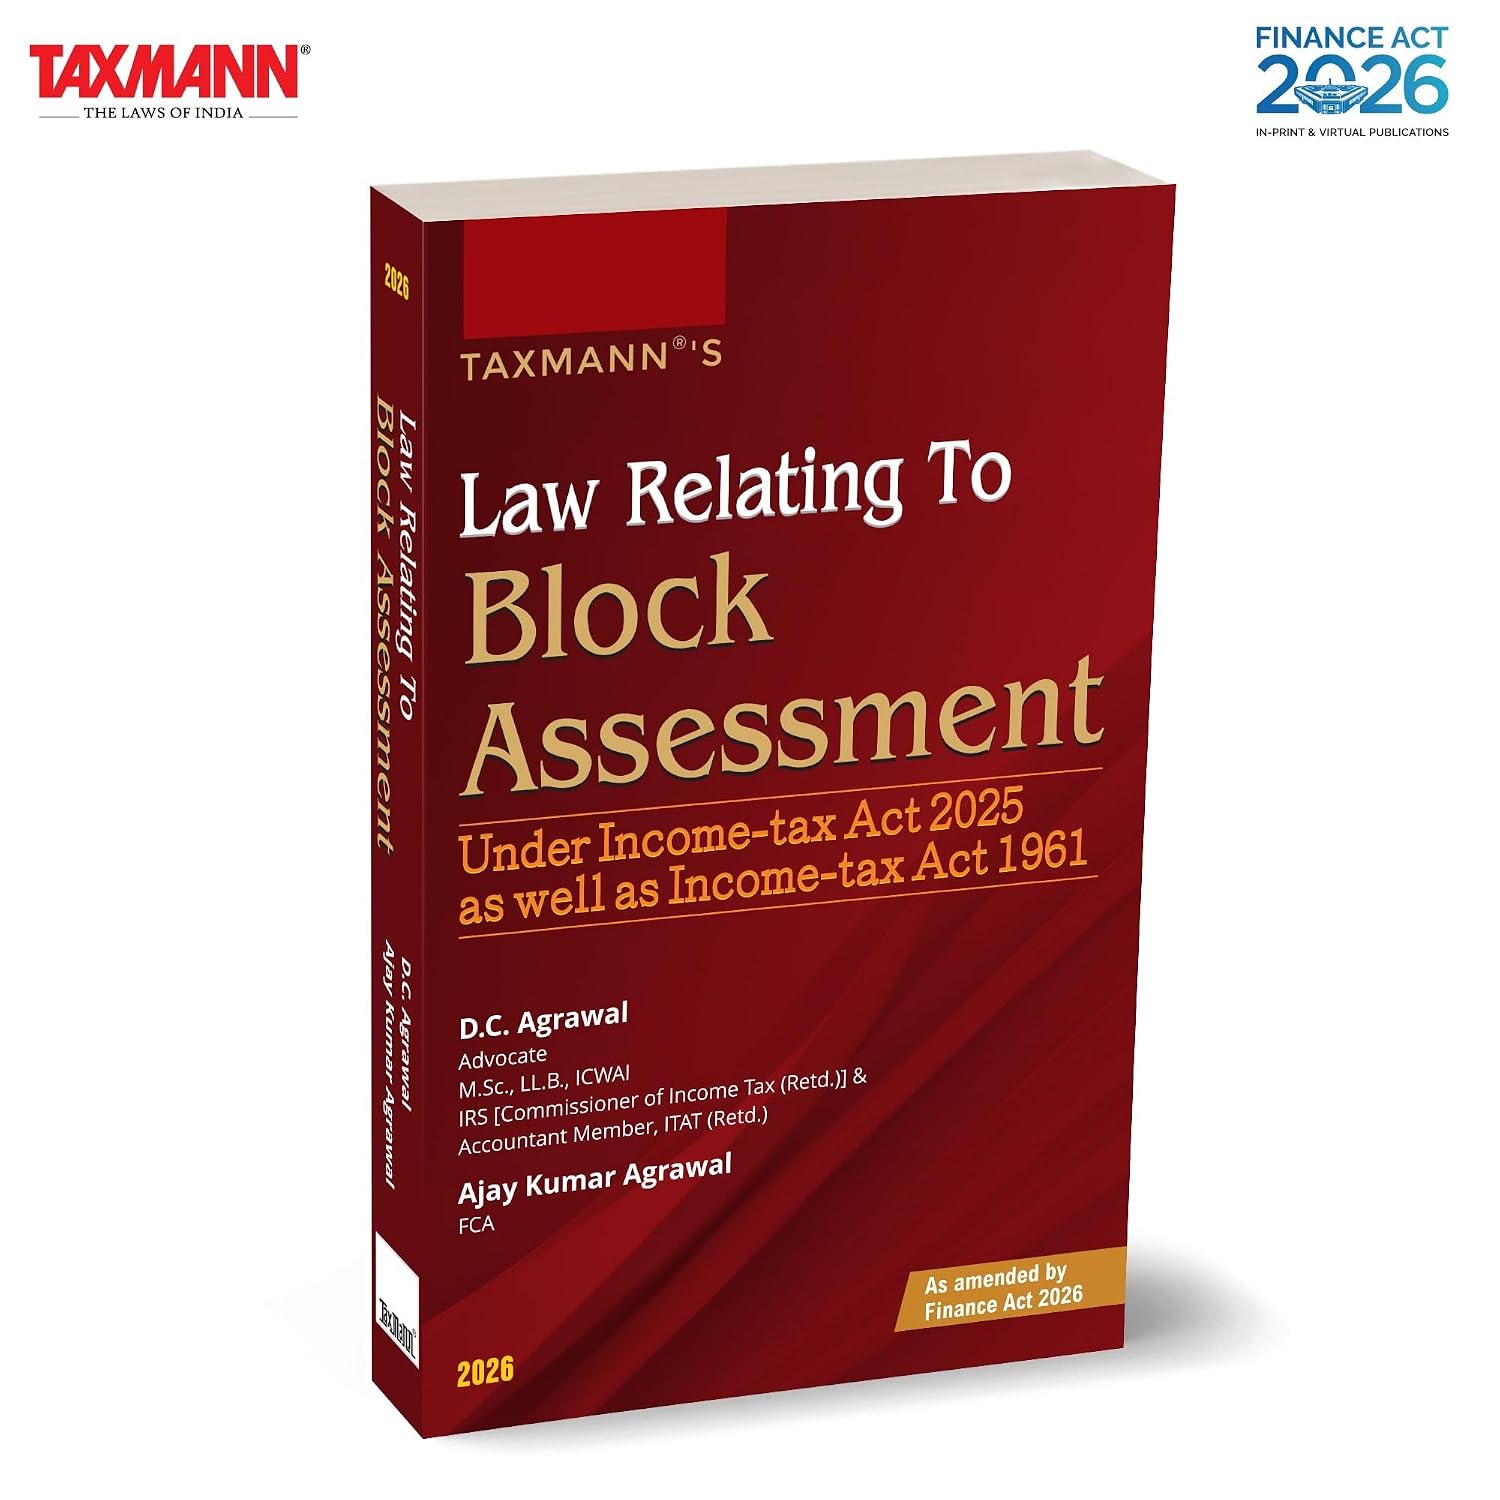
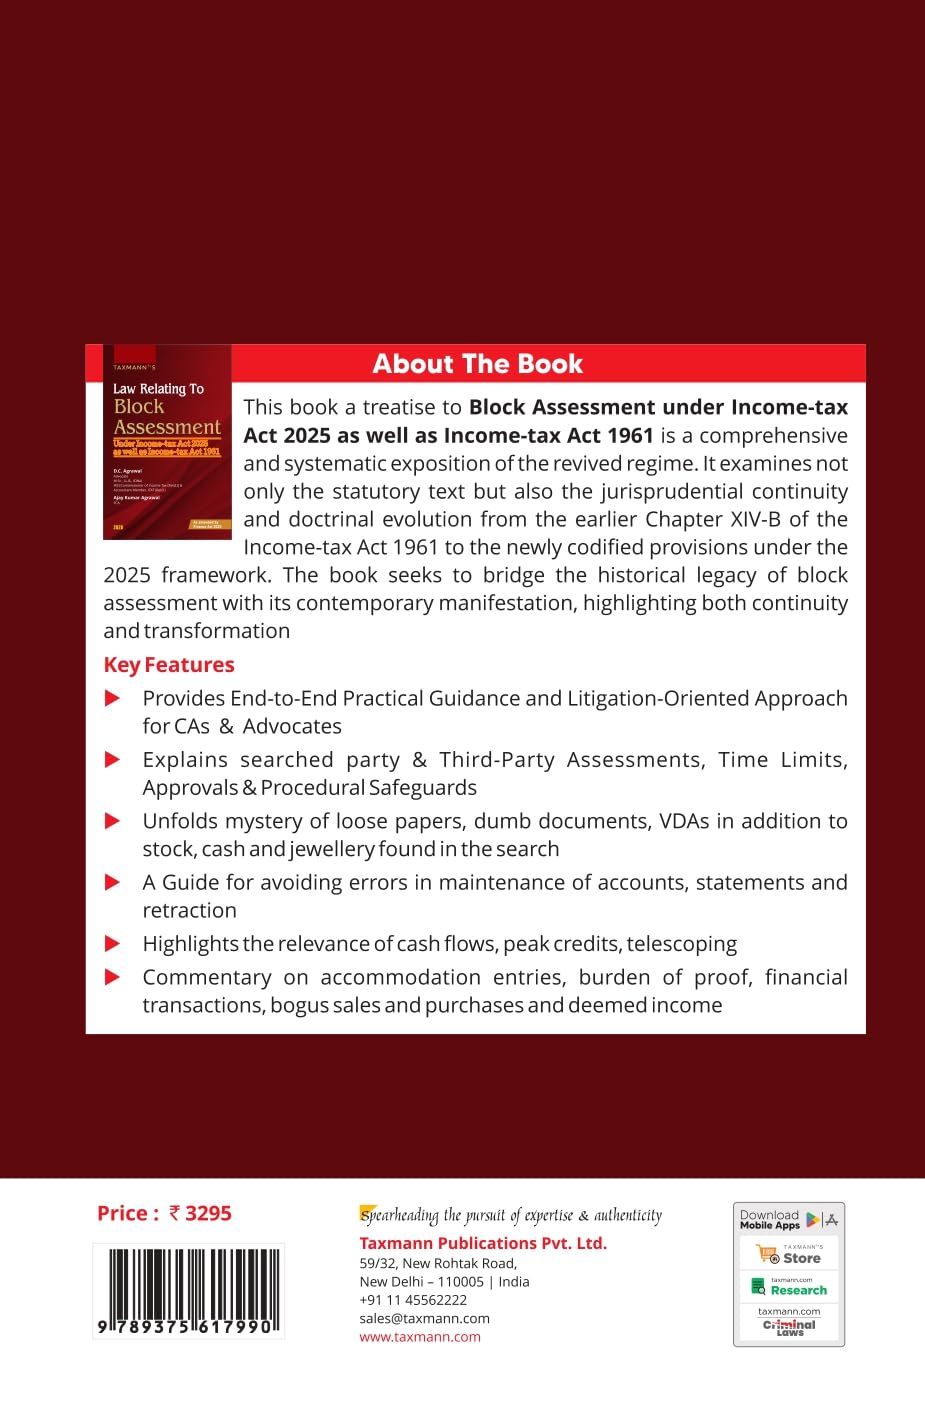
Taxmann’s Law Relating To Block Assessment [Finance Act 2026] – Treatise on the Revived Block
Law Relating To Block Assessment is the leading contemporary work on India’s revived block assessment regime. The reintroduction of block assessment through the Finance (No. 2) Act 2024, its refinement by the Finance Act 2025
Description
Law Relating To Block Assessment is the leading contemporary work on India’s revived block assessment regime. The reintroduction of block assessment through the Finance (No. 2) Act 2024, its refinement by the Finance Act 2025, its consolidation under the Income-tax Act 2025 (operative from 1st April 2026) and its further amendment by the Finance Act 2026 has fundamentally reshaped the architecture of search-driven taxation in India. After two decades of search assessments under Sections 153A to 153C, the legislature has returned to a consolidated block mechanism—but in a modernised form that incorporates digital assets, quarter-based limitation, mandatory supervisory approvals, and harmonised integration with the deemed income regime.
The book’s distinguishing position is that it does not treat block assessment under the 2025 Code as a stand-alone subject. Instead, it reads the new framework against the entire body of Chapter XIV-B jurisprudence developed between 1995 and 2003 and refined through litigation thereafter, and asks, provision by provision, which doctrines survive, which evolve, and which are displaced. The result is the only block assessment treatise that simultaneously serves as a working manual under the 2025 Code and as a continuing reference to the 1961 Act for ongoing litigation, appellate proceedings and pre-2026 search cycles.
The volume is intended as a definitive working reference for:
- Tax Litigators and Senior Advocates appearing in search and block assessment matters before the Tribunal, High Courts and the Supreme Court
- Chartered Accountants and Tax Consultants advising taxpayers on search defence, statement retraction strategy, cash credit explanations, peak credit and telescoping computations, and undisclosed income exposure under Sections 102 to 105
- Assessing Officers, Investigation Wing Officers, Departmental Representatives and Commissioners (Appeals) drafting or adjudicating block assessment orders, satisfaction notes under Section 295, panchnamas, and supervisory approvals under Section 299
- Corporate Heads of Tax, CFOs and In-house Counsel of Business Groups facing or anticipating search and seizure action, particularly those holding digital assets, cross-border positions, or layered investment structures
- Members of the Income Tax Appellate Tribunal and Judicial Officers seeking a consolidated reference on the interplay between the 1961 and 2025 frameworks
- Forensic Accountants, Certified Fraud Examiners, and Investigation Wing Analysts working on the detection side of accommodation entries, shell companies, derivative misclassification, and digitally stored evidence
- Academicians, Post-graduate Law and Accountancy Researchers studying anti-evasion architecture and the transition from Chapter XIV-B to Chapter XVI-B
The Present Publication is the 2026 Edition, amended by the Finance Act 2026. It reflects the Income-tax Act 2025 framework, effective from 1st April 2026, alongside the corresponding jurisprudence under the 1961 Act. It is authored by D.C. Agrawal and Ajay Kumar Agrawal, with the following noteworthy features:
- [Statutory Text-and-Analysis Format] Every key provision is reproduced verbatim, followed by a clause-by-clause ‘Key Features’ exposition covering purpose, scheme placement, sub-section mechanics, evidentiary basis, exclusions, charging linkage, procedural safeguards, taxpayer implications and administrative implications
- [Comprehensive 1961 ↔ 2025 Section Mapping] Explicit cross-walks across the entire Code in tabular and narrative form, allowing the reader to navigate seamlessly between corresponding provisions of the two statutes
- [Over 2,500 Judicial Precedents] Supreme Court, High Court and Tribunal decisions integrated by ratio under each sub-issue, with explicit testing of pre-2025 Chapter XIV-B authorities for continued applicability under the new Code
- [Three-Part Manner-of-Operation/Example/Defence Treatment] For each manipulation pattern in the forensic and financial transactions chapters, the reader is provided the modus operandi, a worked rupee-denominated example, and the documentary defence package
- [Dual-Lens Drafting] Every chapter reflects both the assessing-authority view (how to draft, defend and adjudicate) and the taxpayer-defence view (what paperwork discharges the shifting onus), driven by the authors’ combined Tribunal-bench and litigation-practice experience
- [Comparative Tables and Illustrative Situations] Embedded throughout for rapid navigation across the two statutory regimes
- [Case-by-Case Digital Evidence Taxonomy] Separate compilations of decisions where Section 65B/Bharatiya Sakshya Adhiniyam certification was correctly invoked and admitted, where it was improperly invoked or absent and the evidence was rejected, and where the certificate was held not to be required
- [Practitioner-Ready Apparatus] Each chapter concludes with a ‘Guidelines’ section synthesising actionable principles, followed by a ‘Conclusion’ crystallising the doctrinal position; rebuttal templates and CBDT instruction summaries are embedded where relevant
- [Consolidated List of Cases and Subject Index] Over 80 pages of case citations and a granular subject index keyed to paragraph numbers, enabling targeted retrieval
2 reviews for Taxmann’s Law Relating To Block Assessment [Finance Act 2026] – Treatise on the Revived Block
Related products
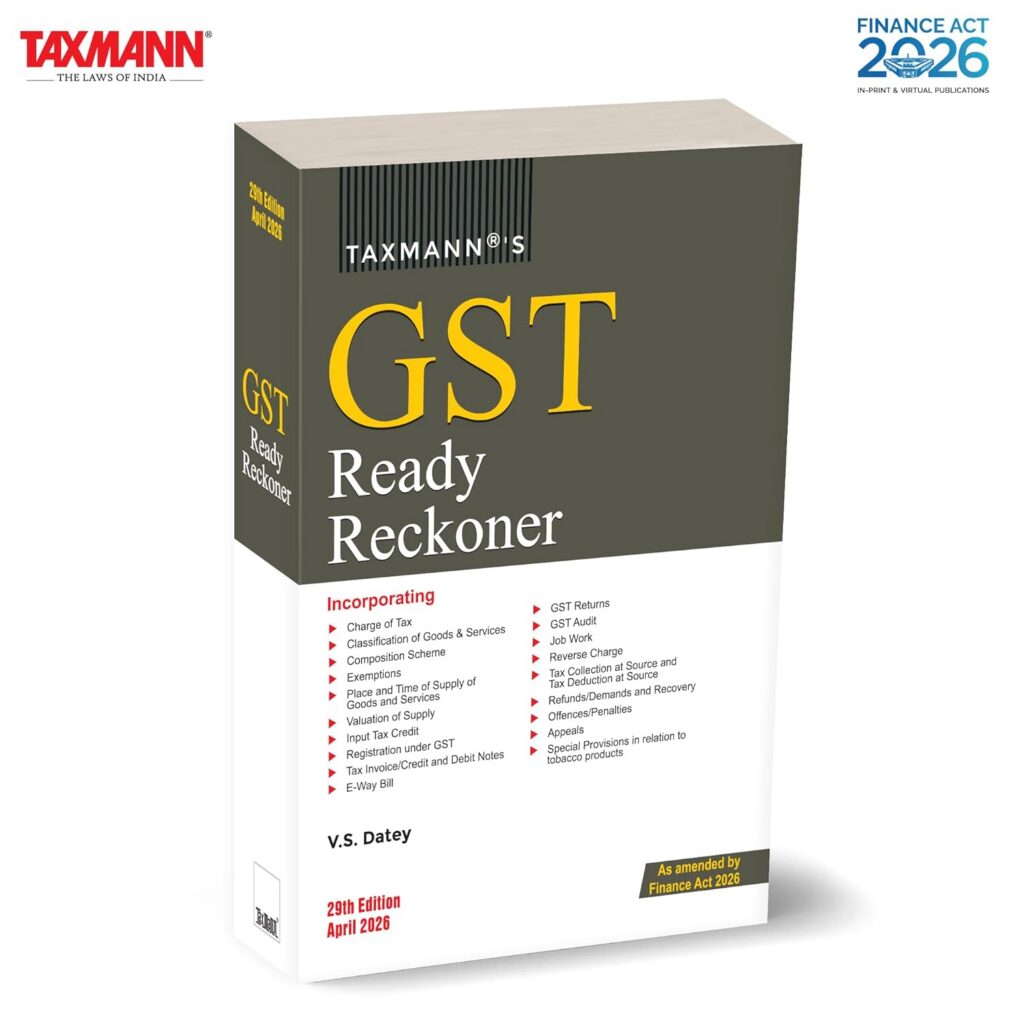
Taxmann’s GST Ready Reckoner [Finance Act 2026] – The Trusted Single-volume GST Reference
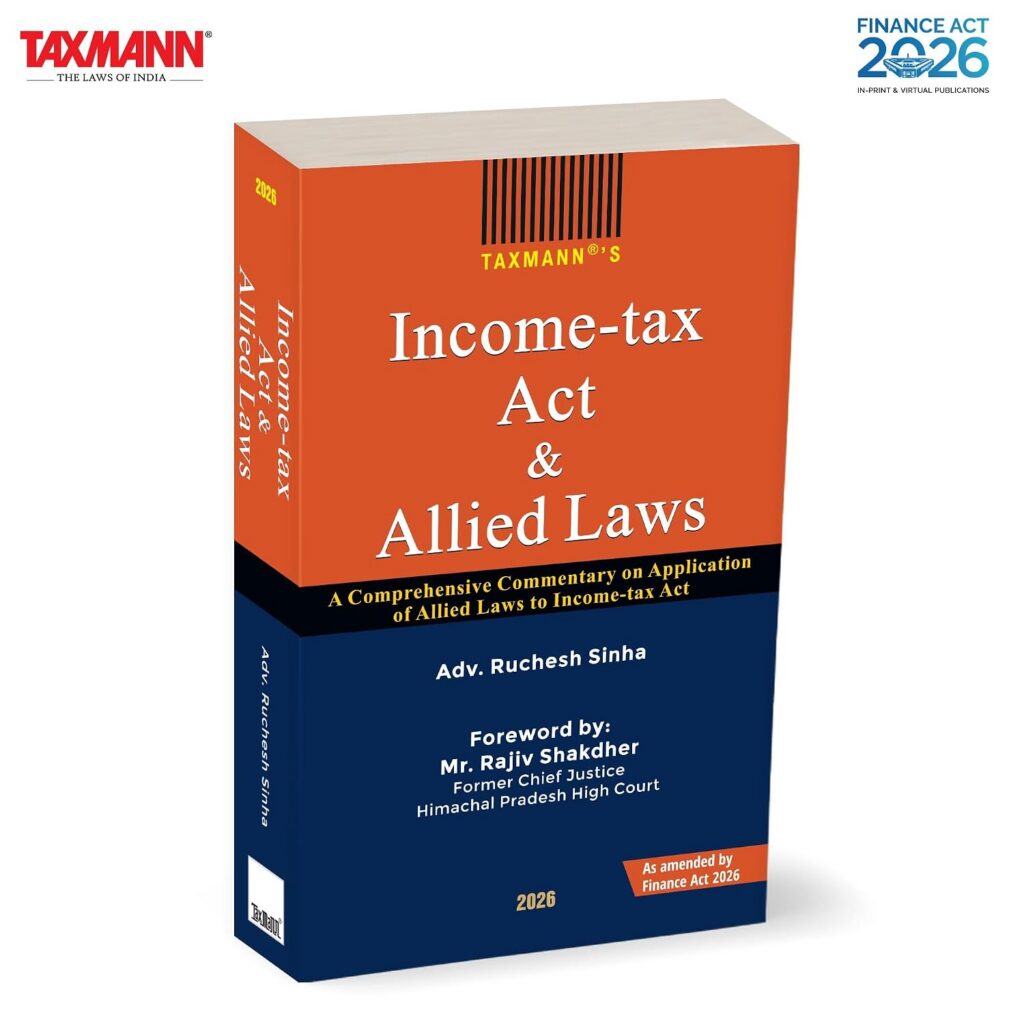
Taxmann’s Income-tax Act & Allied Laws [Finance Act 2026] – First Structured Resource To Map
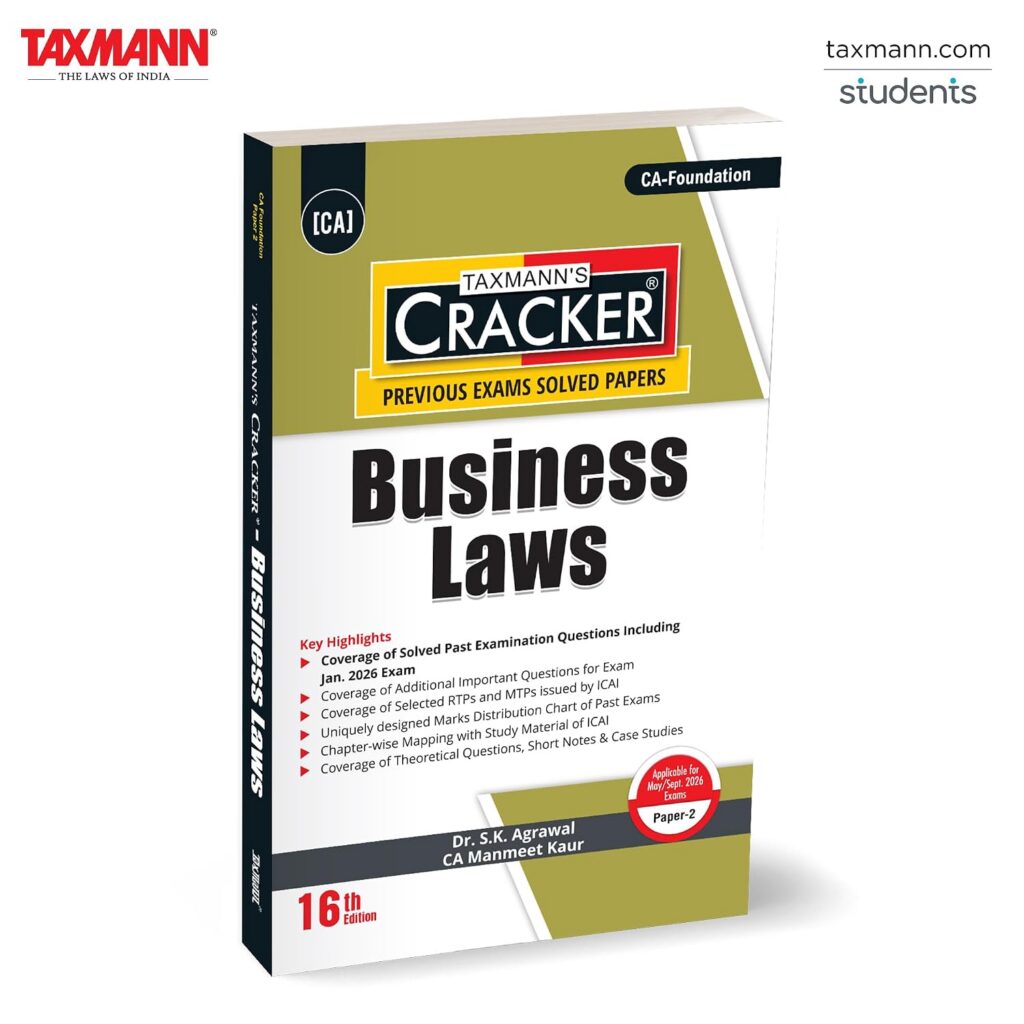
Taxmann’s CRACKER for Business Laws (Paper 2 | Law) – Final-stage | Exam-focused Practice Manual
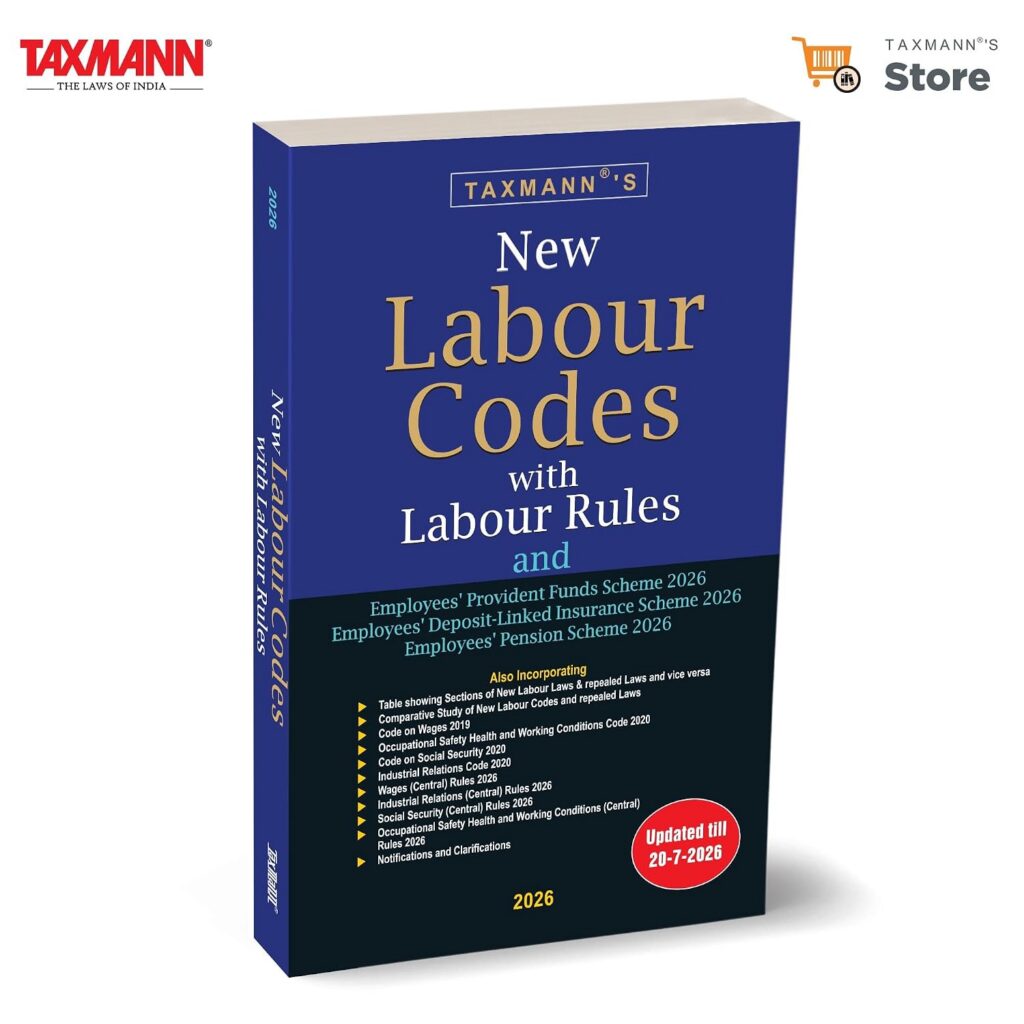
Taxmann’s New Labour Codes with Labour Rules – Single-volume Desk Companion Bringing
Before You Start Up : How to Prepare to Make Your Startup Dream a Reality
admin –
Sed perspiciatis unde omnis iste natus error sit voluptatem accusantium doloremque laudantium.
admin –
Sed perspiciatis unde omnis iste natus aliquam sit voluptatem exercitationem doloremque laudantium.