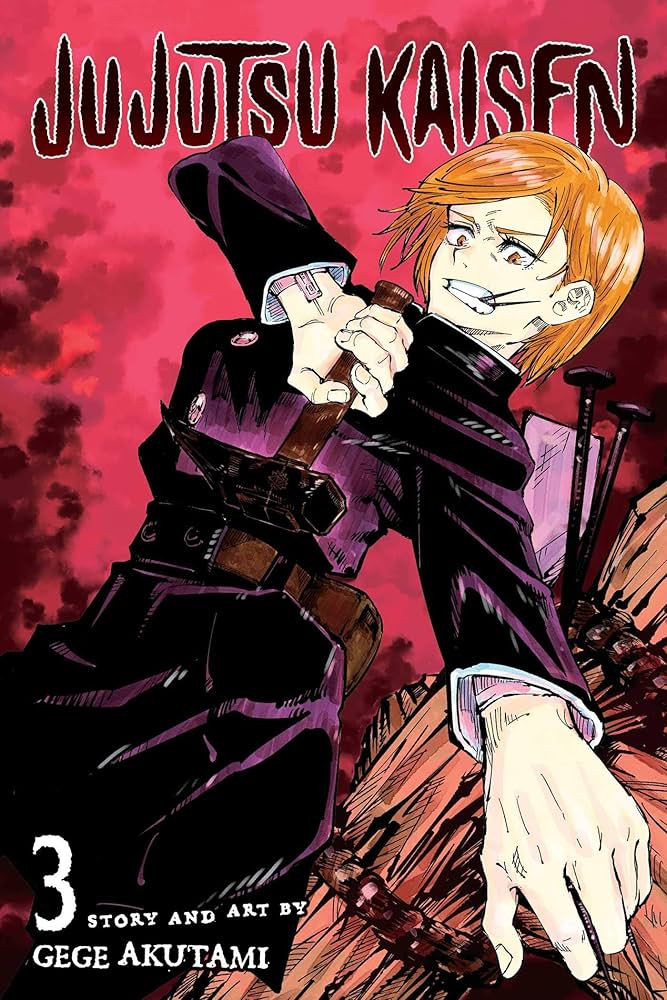
Jujutsu Kaisen, Vol. 3 (Volume 3) Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.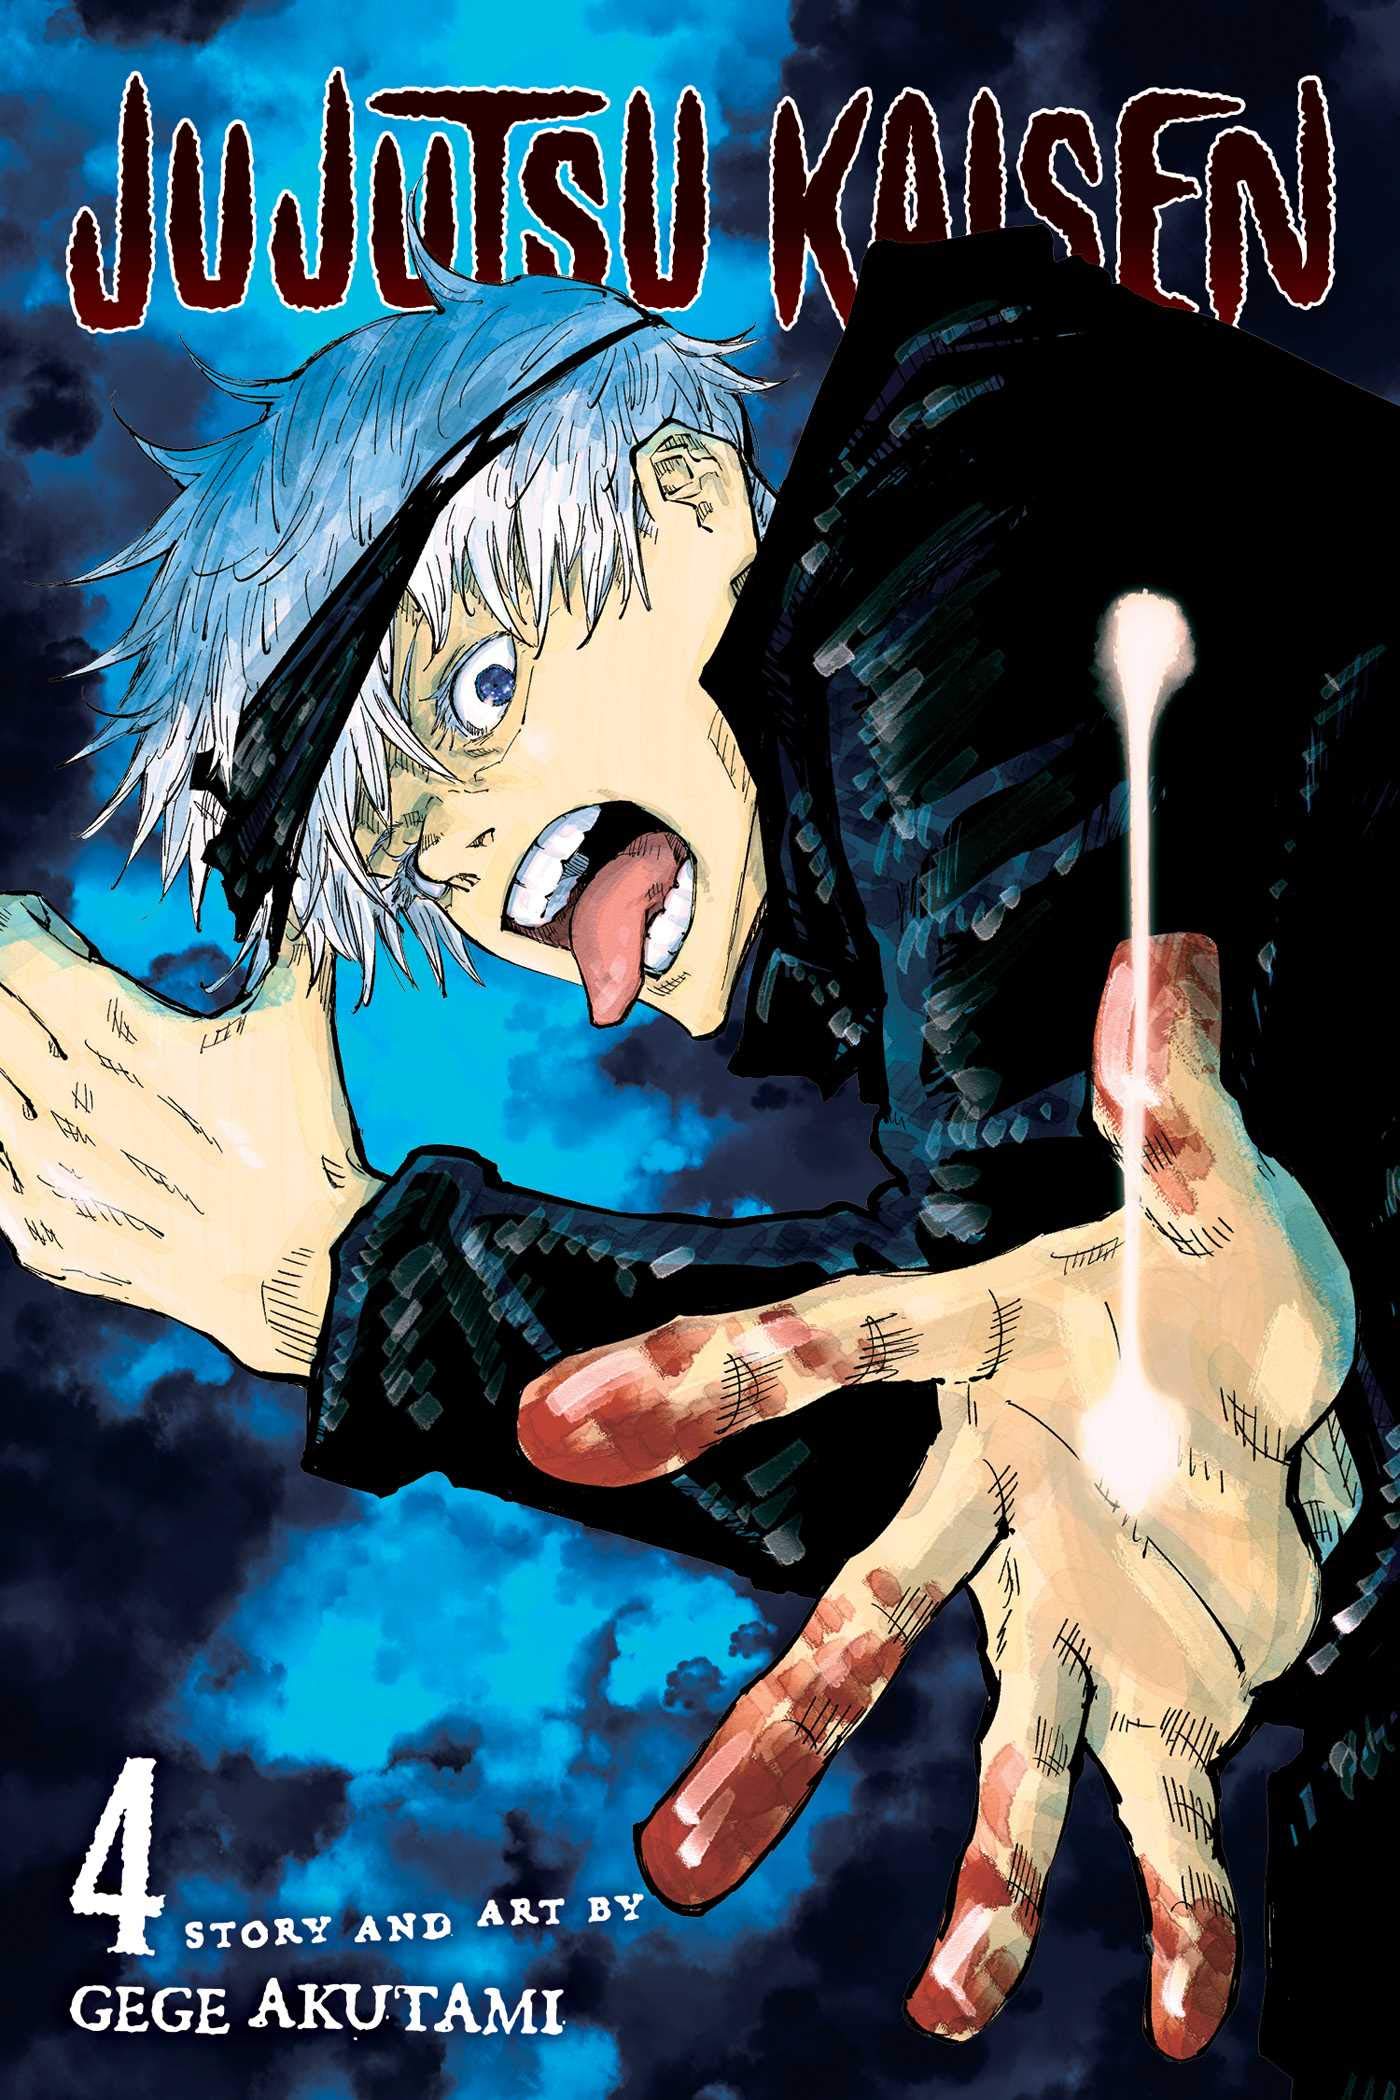
Jujutsu Kaisen, Vol. 04: Volume 4 Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.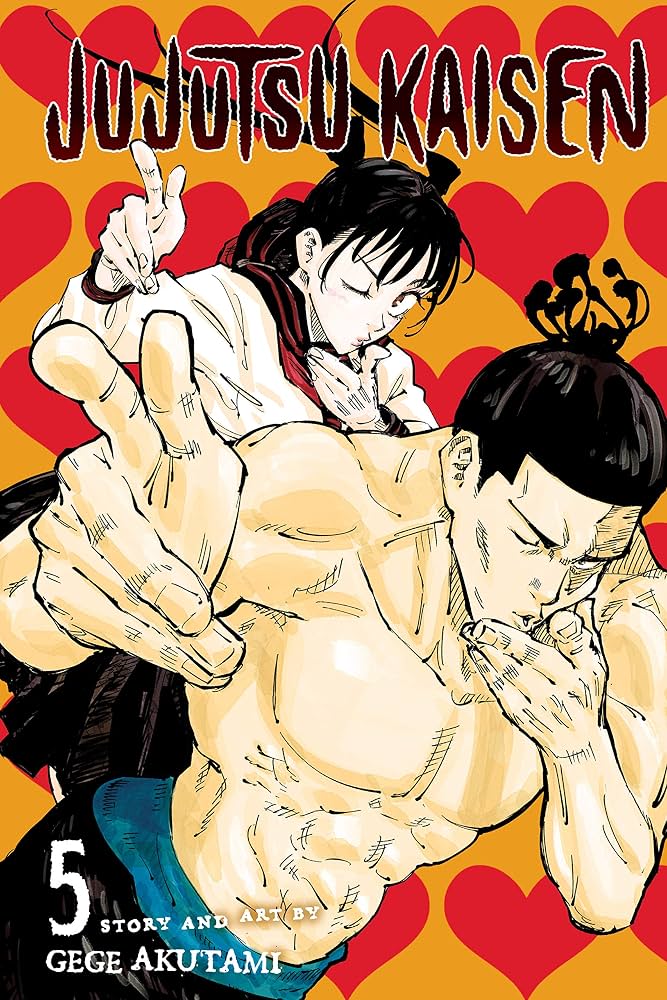
Jujutsu Kaisen, Vol. 5: Volume 5 Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.
Jujutsu Kaisen, Vol. 02 Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.
Jujutsu Kaisen, Vol. 1: Volume 1
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.
The 7 Habits of Highly Effective People Paperback
Original price was: ₹499.00.₹249.00Current price is: ₹249.00.
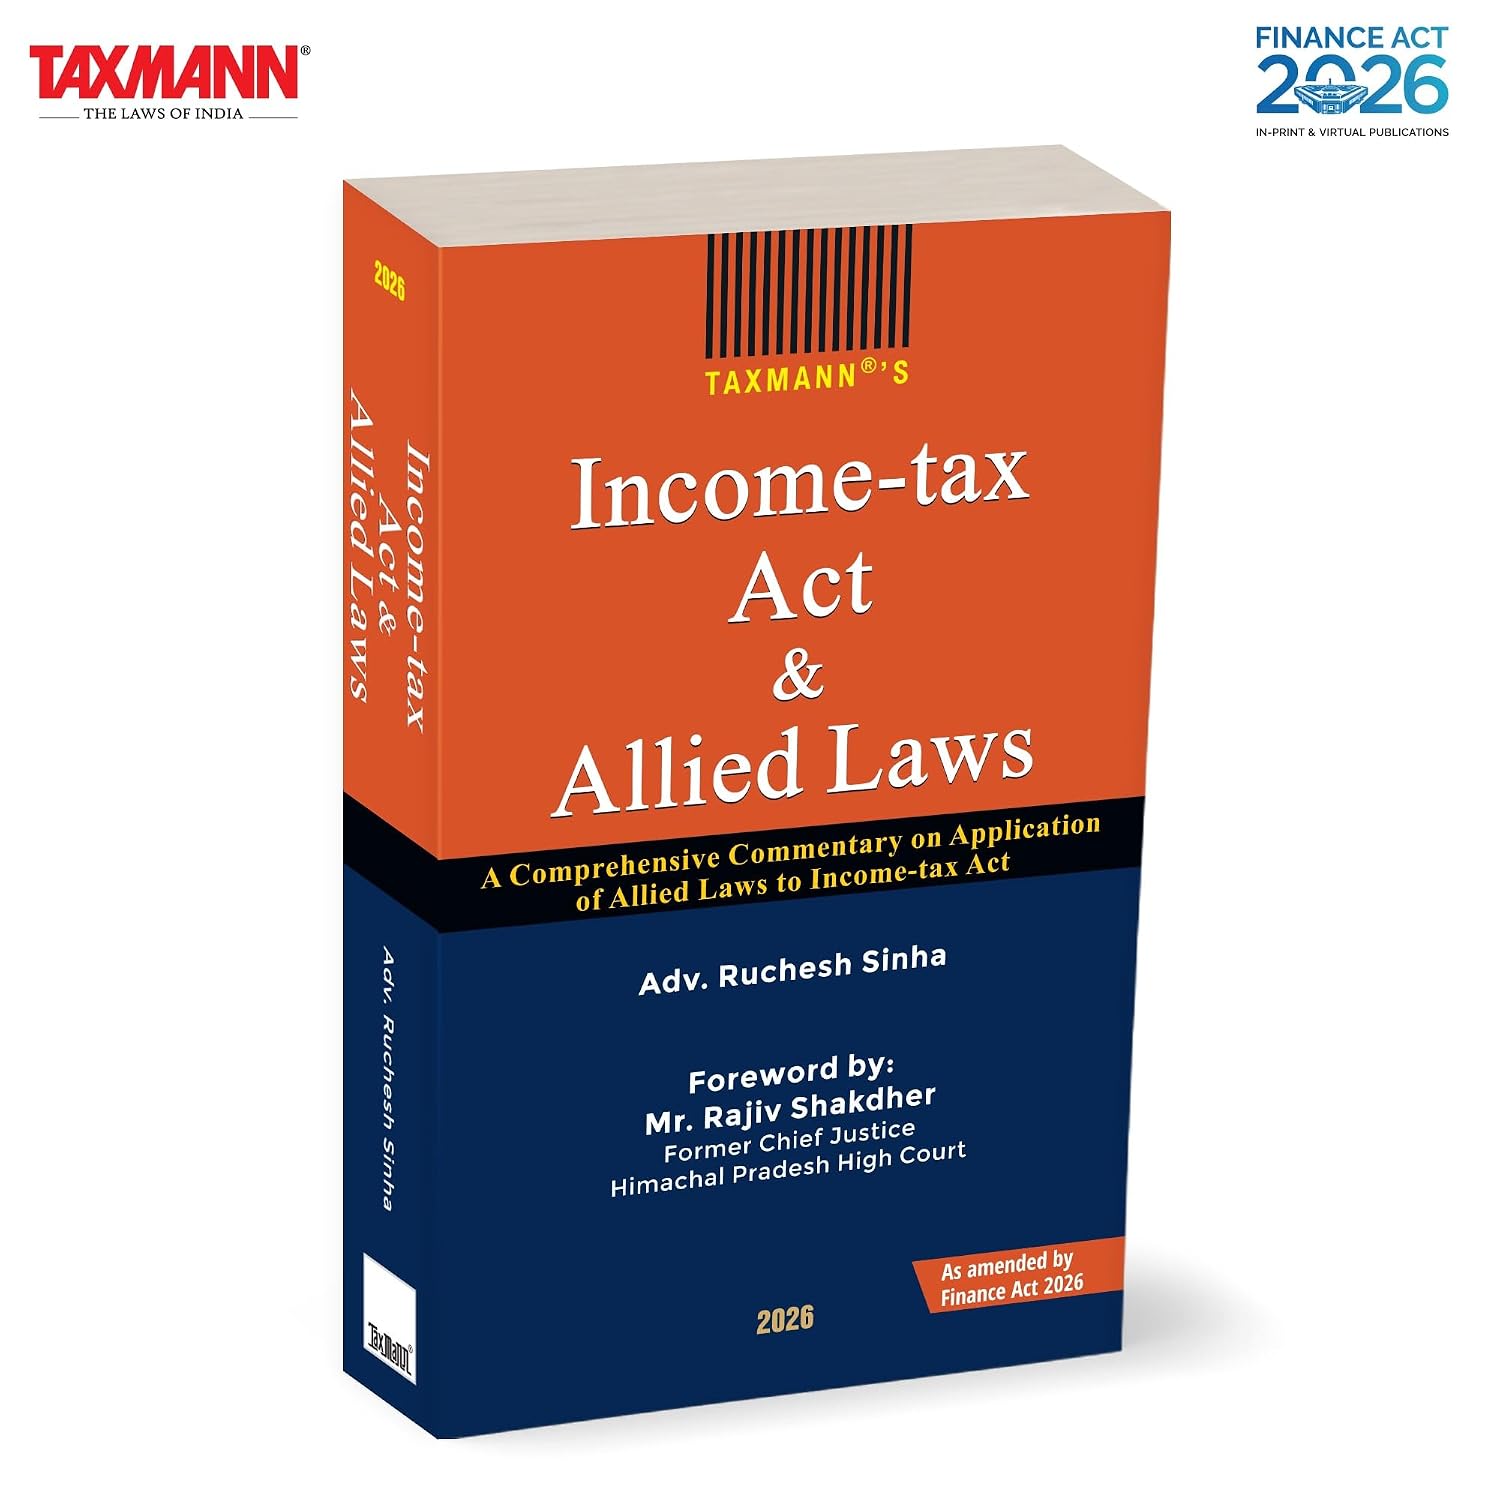
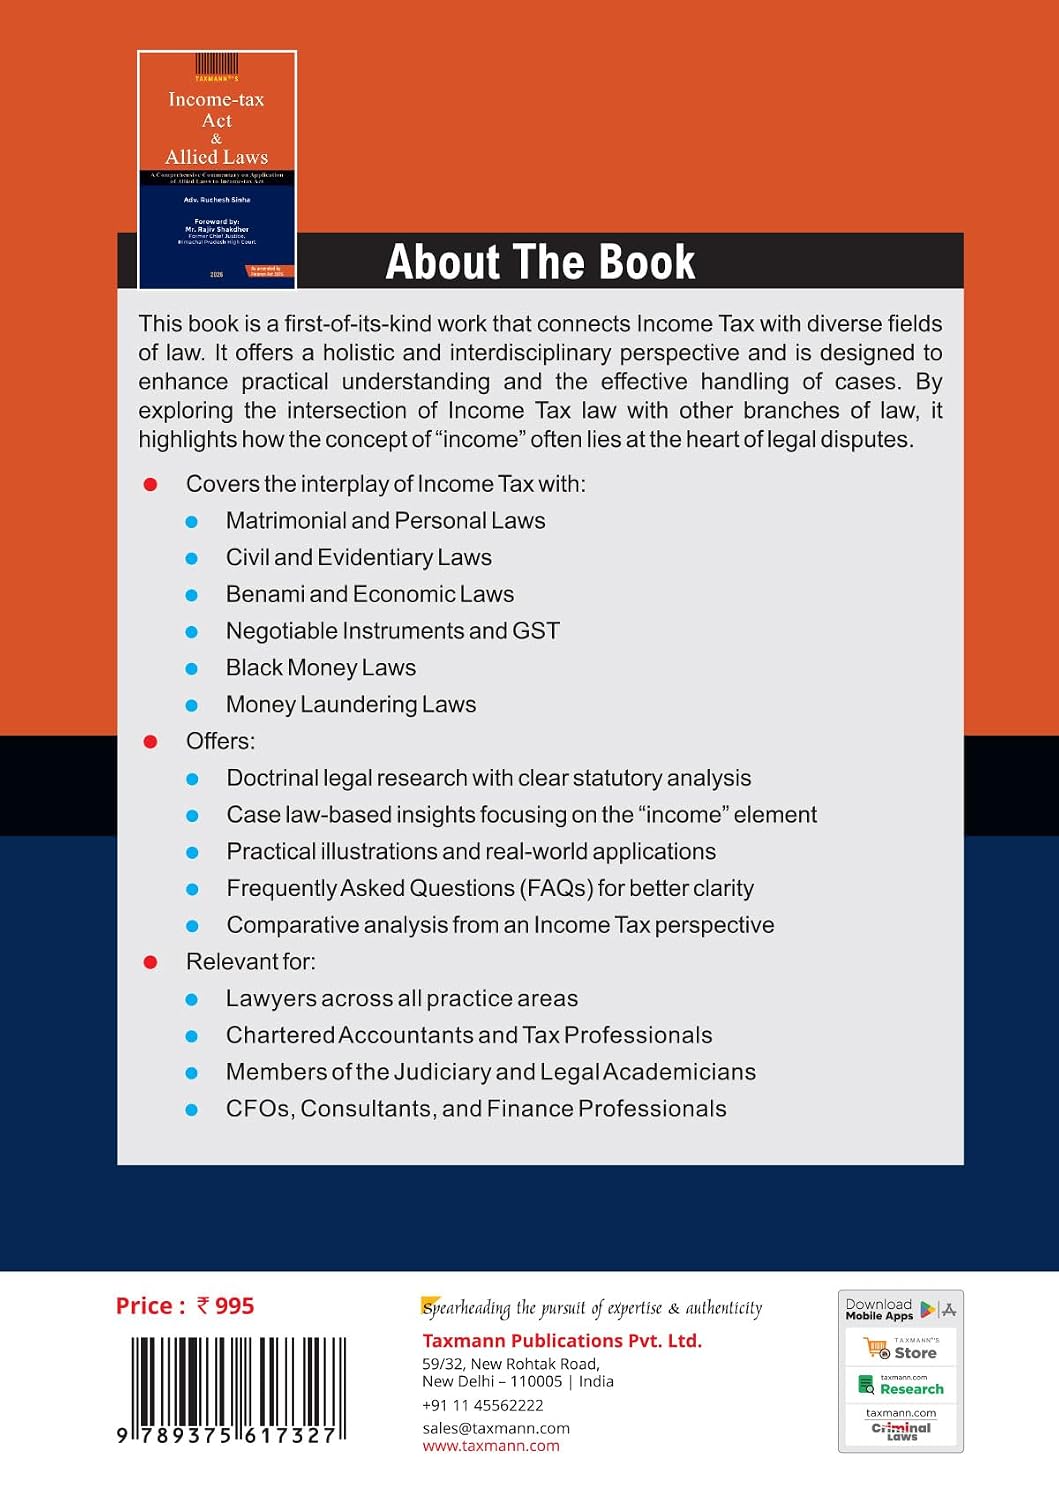
Taxmann’s Income-tax Act & Allied Laws [Finance Act 2026] – First Structured Resource To Map
Income-tax Act & Allied Laws is a first-of-its-kind interdisciplinary legal commentary that maps, with statutory precision and courtroom depth, exactly where and how the Income-tax Act 2025 collides with, qualifies, supplements, and sometimes overrides ten other major Indian statutes.
Description
Income-tax Act & Allied Laws is a first-of-its-kind interdisciplinary legal commentary that maps, with statutory precision and courtroom depth, exactly where and how the Income-tax Act 2025 collides with, qualifies, supplements, and sometimes overrides ten other major Indian statutes. The premise of the book is both bold and self-evident: income, as the economic substratum of all human activity, permeates every field of law, and yet the legal profession has historically treated taxation as a discipline in isolation. Courts adjudicate matrimonial disputes, cheque dishonour cases, benami attachment proceedings, PMLA prosecutions, and corporate fraud matters with near-complete disregard for what the Income-tax Act has already established about the financial position of the parties—often to the material detriment of the outcome.
The commentary covers eleven distinct statutory intersections across twelve chapters, progressing from the foundational structure of the ITA 2025 through matrimonial law, evidentiary law, civil law, negotiable instruments law, benami law, GST, PMLA, black money law, cash regulation, and corporate law. Each chapter is built around verbatim reproduction of the key provisions of both the ITA and the allied statute, followed by the author’s detailed analytical notes, cross-statutory mapping, annotated case law with ratio extracted, and a structured FAQ section designed for deployment-ready use by practitioners in drafting, litigation, advisory, and adjudication.
The book is explicitly addressed to a multi-disciplinary readership that extends well beyond the conventional income tax audience:
- Legal Practitioners in civil, criminal, family, corporate, and commercial domains who encounter financial evidence, income disclosures, or tax-linked claims in their matters
- Tax Consultants and Chartered Accountants who need to understand the cross-statutory implications of their advisory work
- Corporate Tax Managers, CFOs, and Finance Heads who must navigate simultaneous obligations under the ITA, CGST, PMLA, and Companies Act
- International Tax Advisors and Wealth Management Advisors dealing with cross-border transactions, foreign asset disclosures, and double taxation frameworks
- Revenue Officers and Departmental Representatives who handle prosecution, search, survey, and enforcement proceedings
- Members of the Judiciary—Trial Court judges, ITAT Members, and High Court benches—who must assess the admissibility and weight of income tax records as evidence
- Academicians and Law Students pursuing tax law, constitutional law, or interdisciplinary legal studies
2 reviews for Taxmann’s Income-tax Act & Allied Laws [Finance Act 2026] – First Structured Resource To Map
Related products
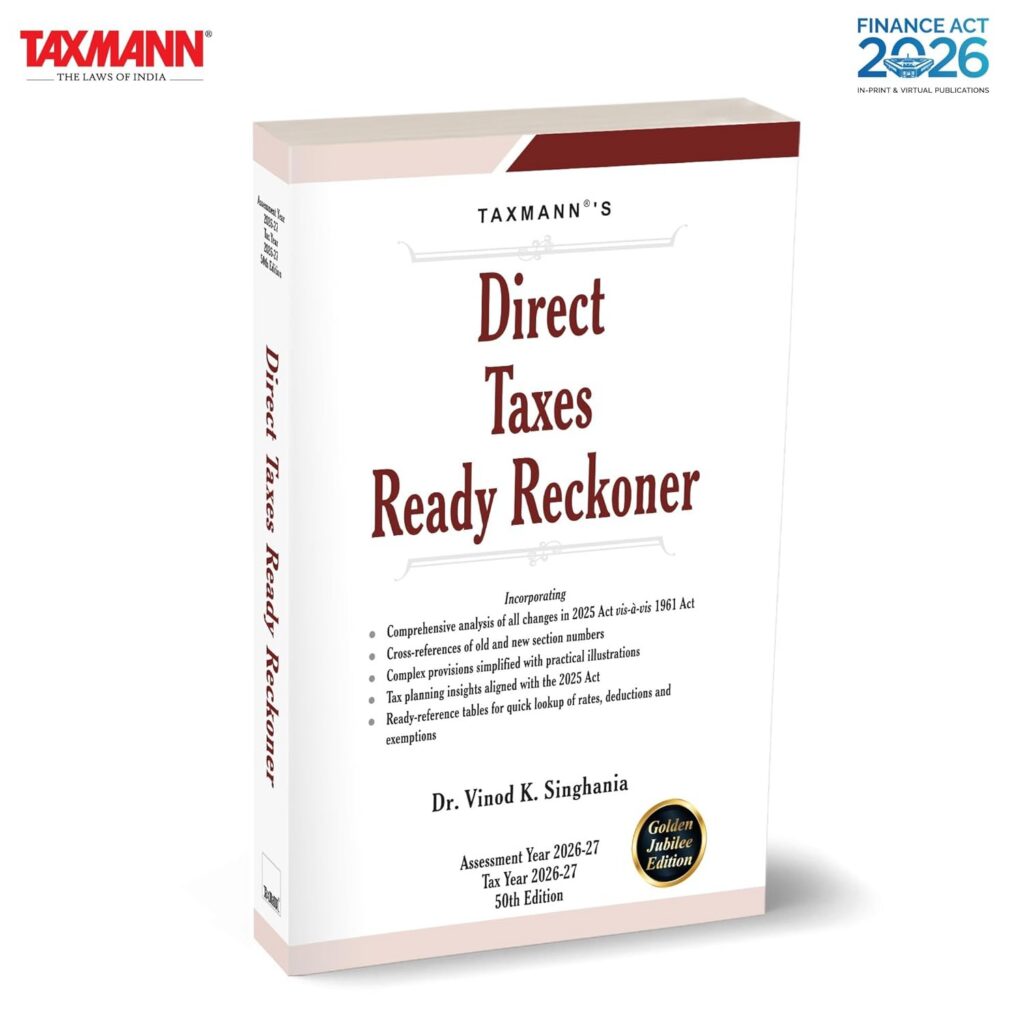
Taxmann’s Direct Taxes Ready Reckoner (DTRR) [Finance Act 2026] – India’s Most Comprehensive Reference
PW UPSC Mindmaps Economy For UPSC/PSC Competitive Examinations | Navigating Concepts
PARMAR SSC Fatman | GK/GS Theory Book | English Medium | 2nd Edition, 2026
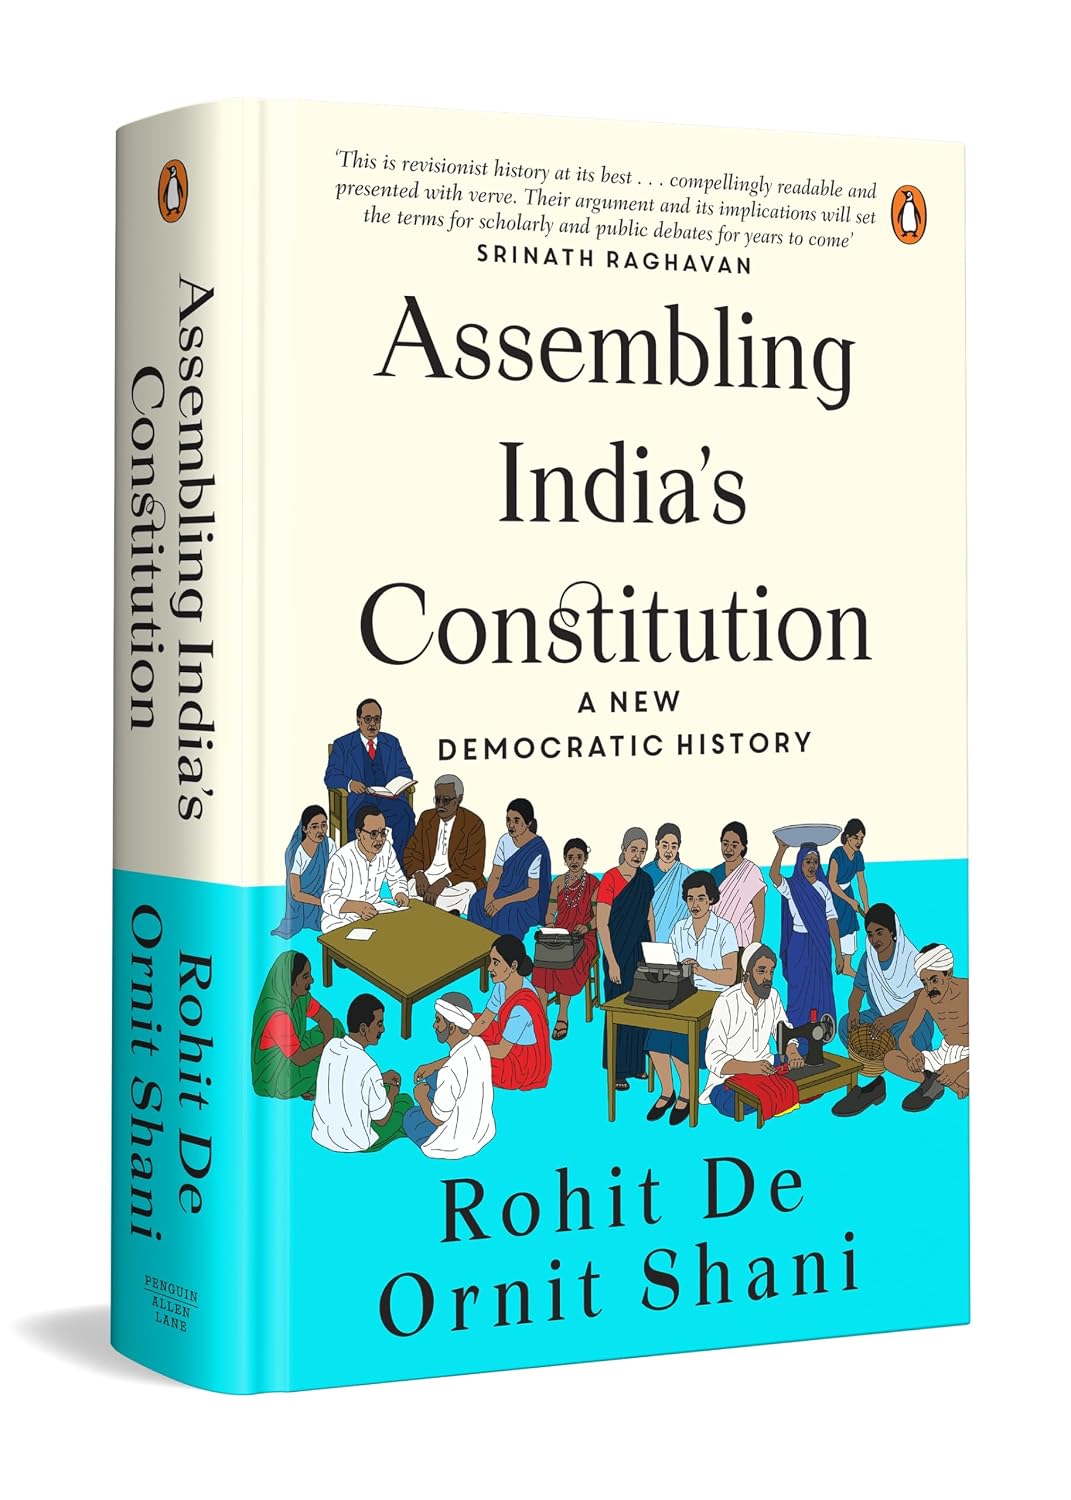
Assembling India’s Constitution: A New Democratic History | How Citizens, Communities
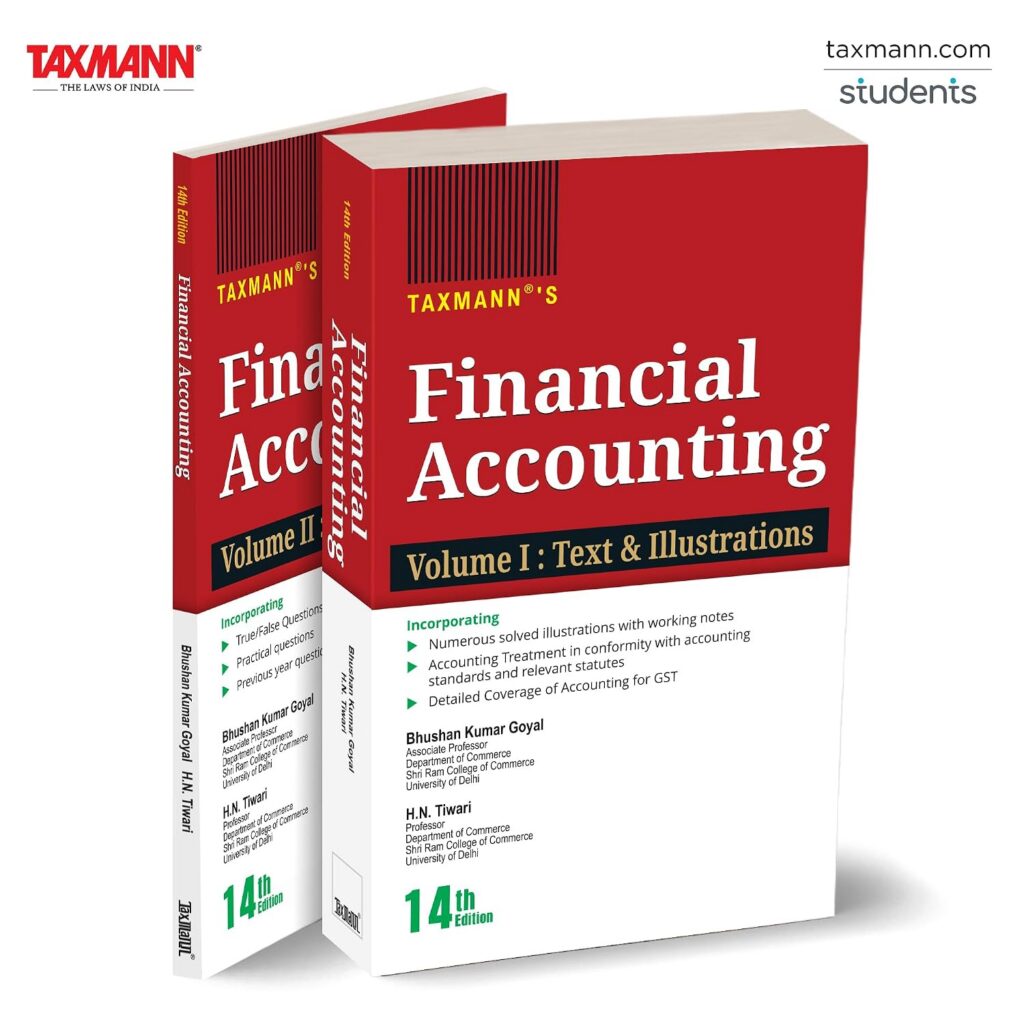
Taxmann’s Financial Accounting [UGCF | NEP] – Two-Volume Textbook for B.Com./B.Com. (Hons.) Students
admin –
Sed perspiciatis unde omnis iste natus error sit voluptatem accusantium doloremque laudantium.
admin –
Sed perspiciatis unde omnis iste natus aliquam sit voluptatem exercitationem doloremque laudantium.