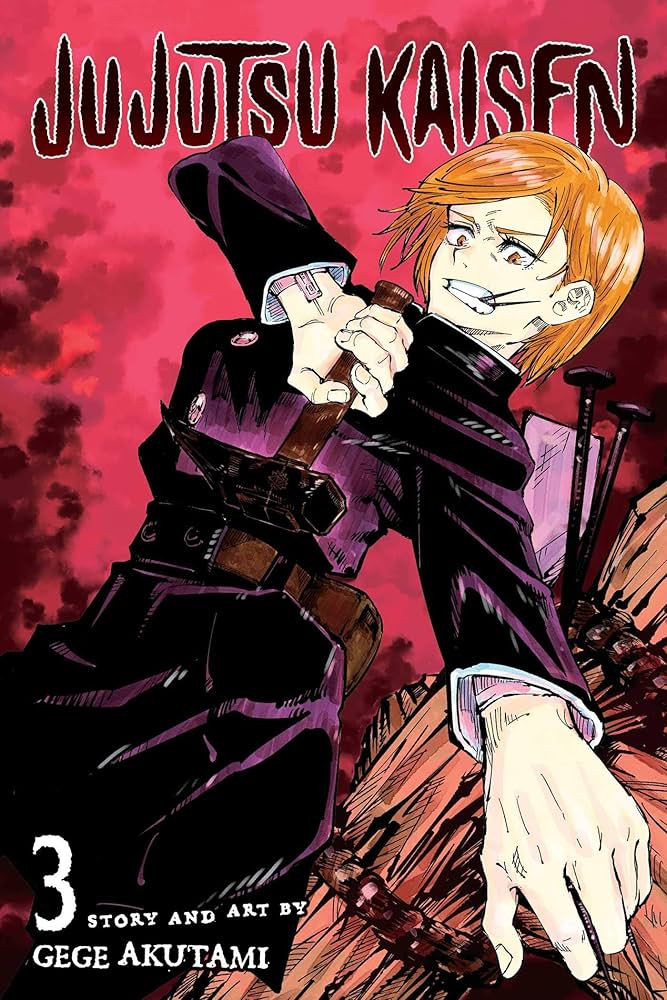
Jujutsu Kaisen, Vol. 3 (Volume 3) Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.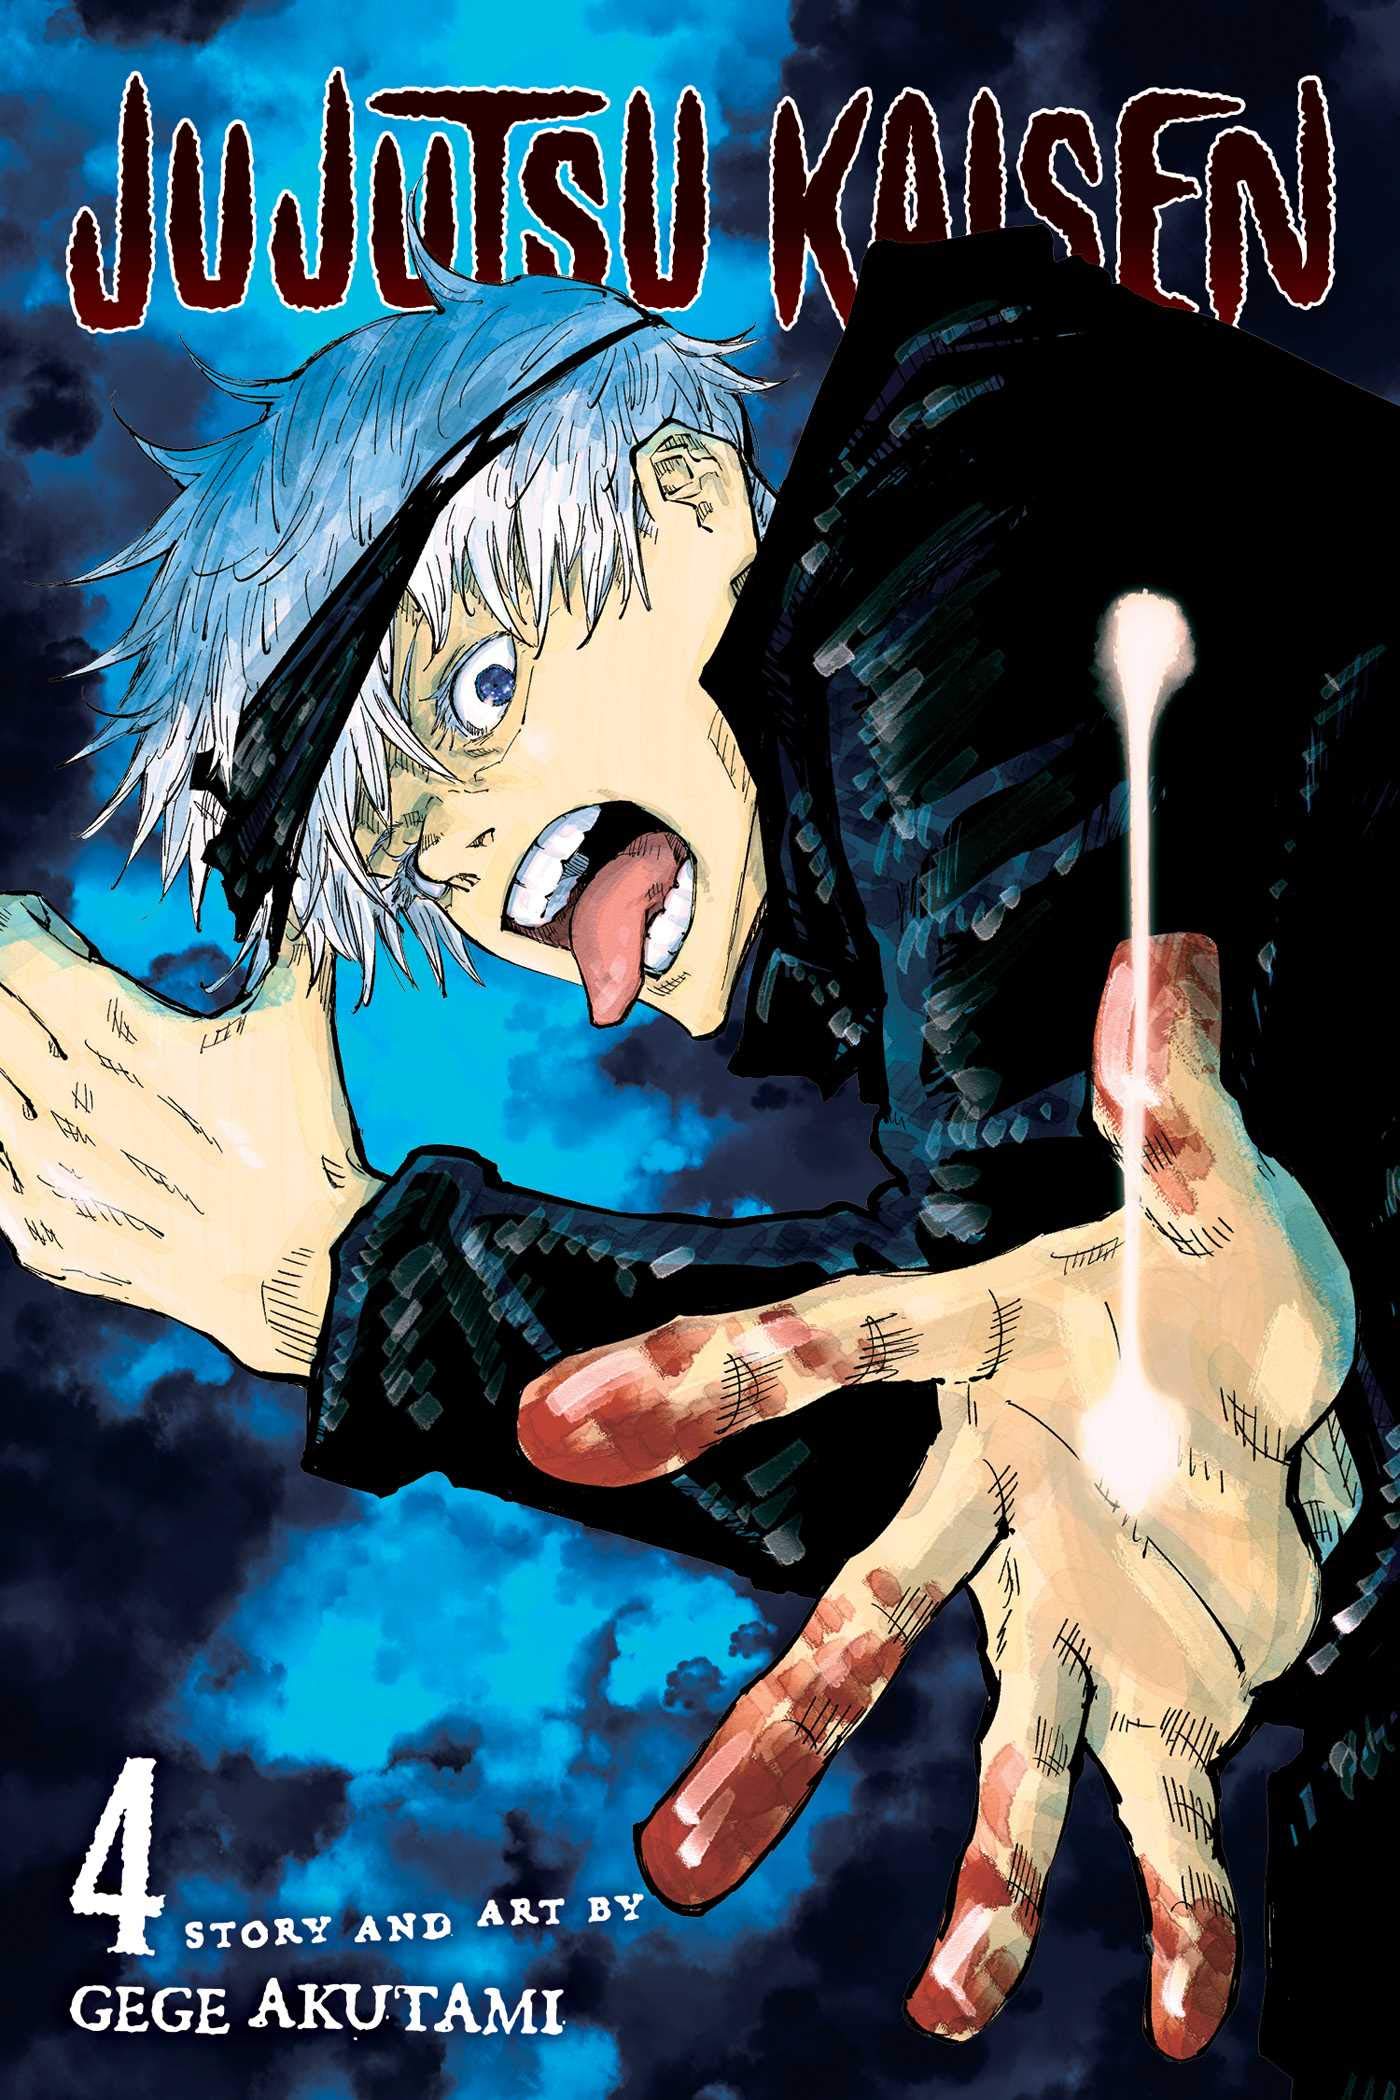
Jujutsu Kaisen, Vol. 04: Volume 4 Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.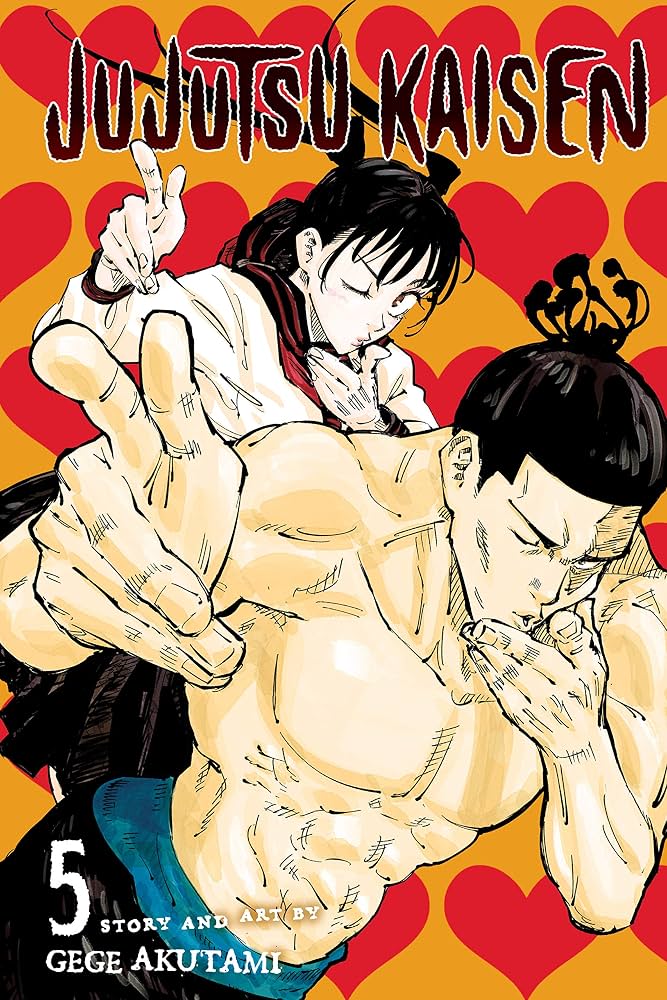
Jujutsu Kaisen, Vol. 5: Volume 5 Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.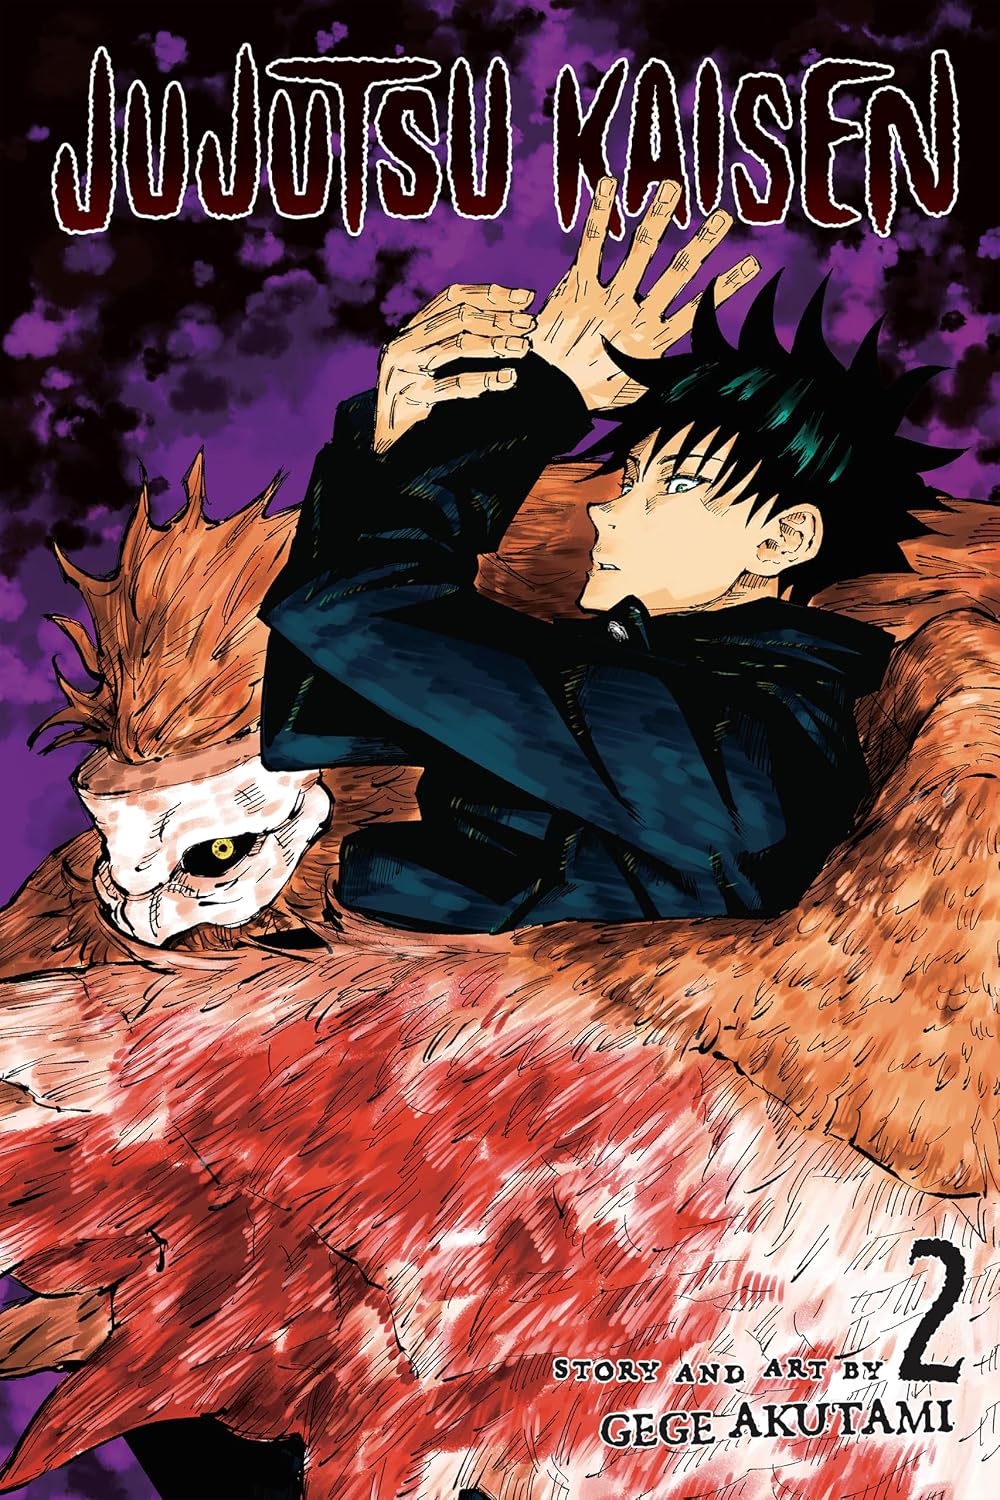
Jujutsu Kaisen, Vol. 02 Paperback
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.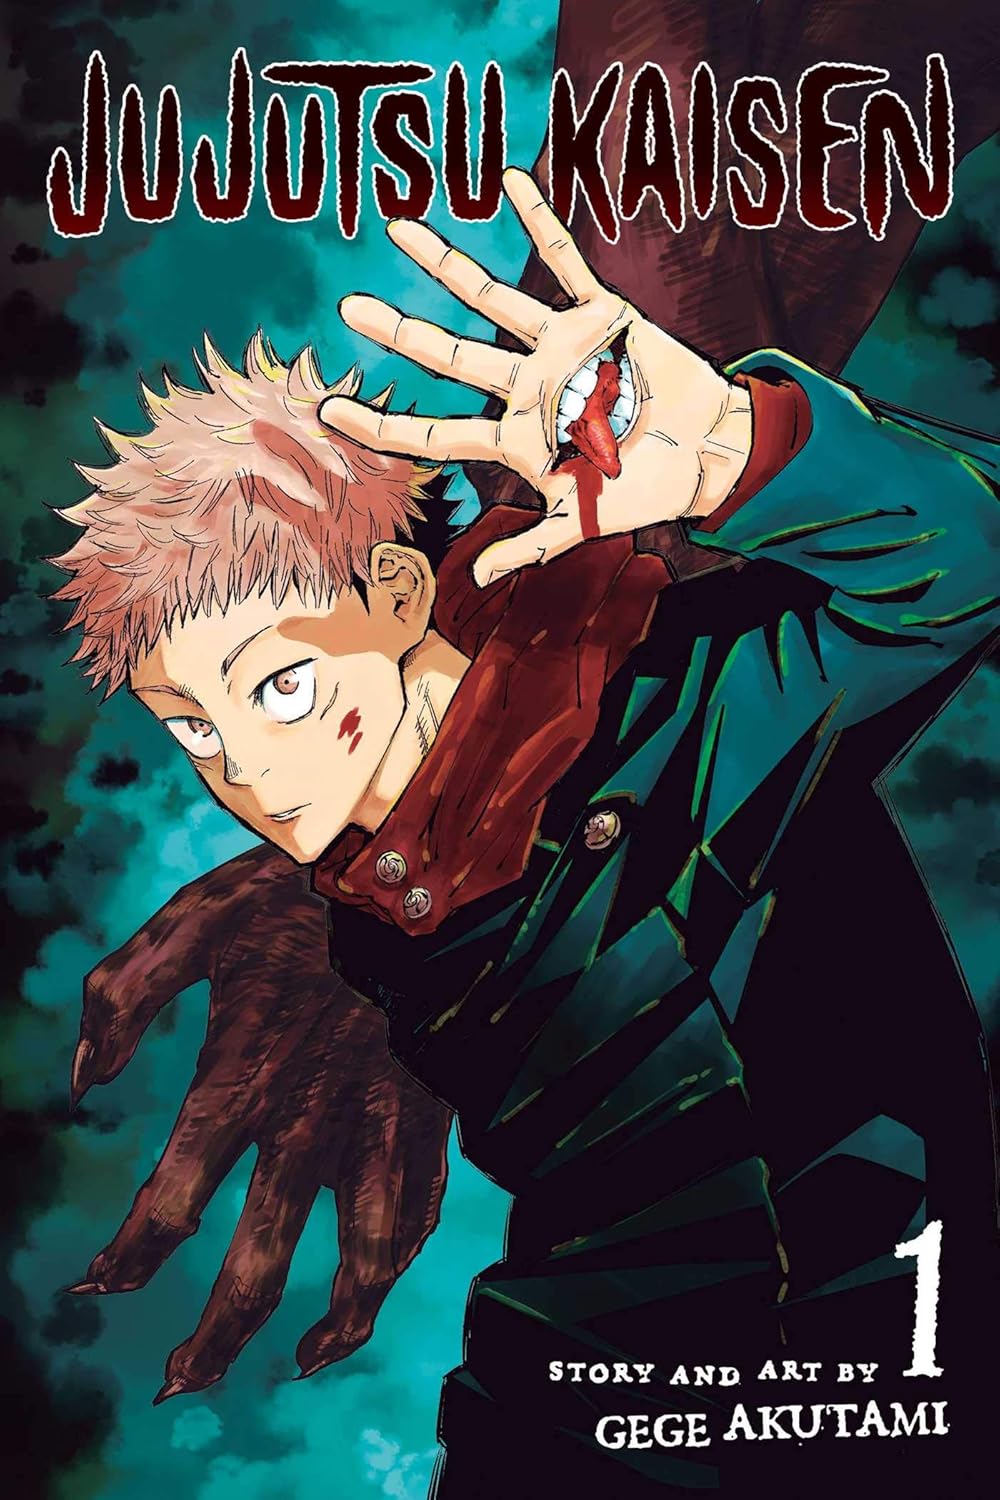
Jujutsu Kaisen, Vol. 1: Volume 1
Original price was: ₹799.00.₹299.00Current price is: ₹299.00.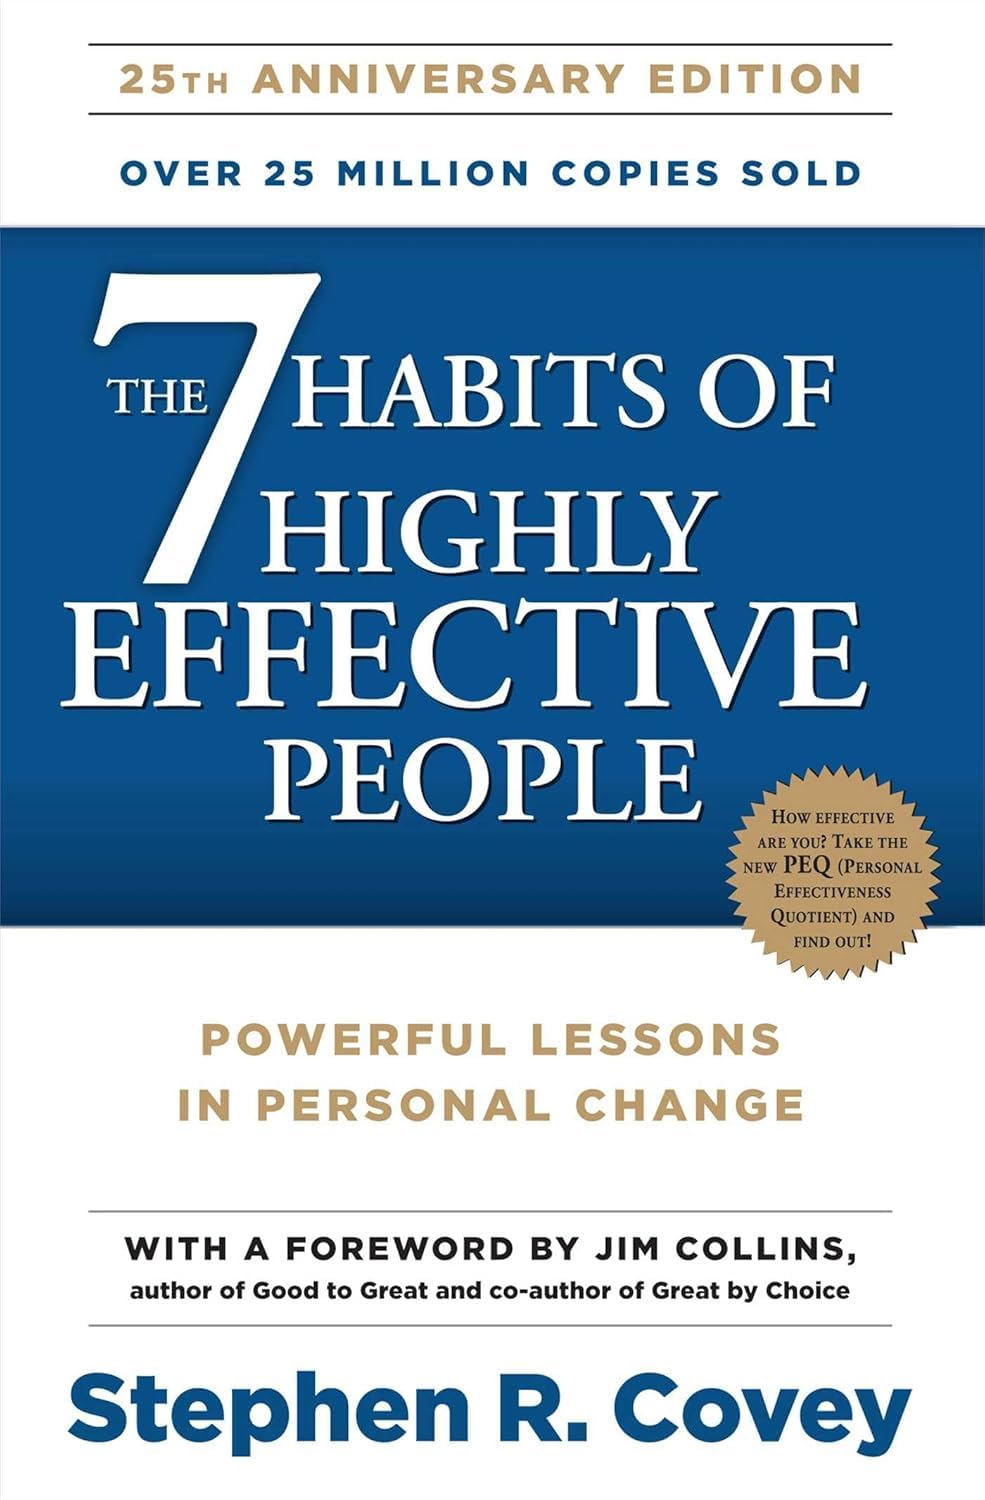
The 7 Habits of Highly Effective People Paperback
Original price was: ₹499.00.₹249.00Current price is: ₹249.00.
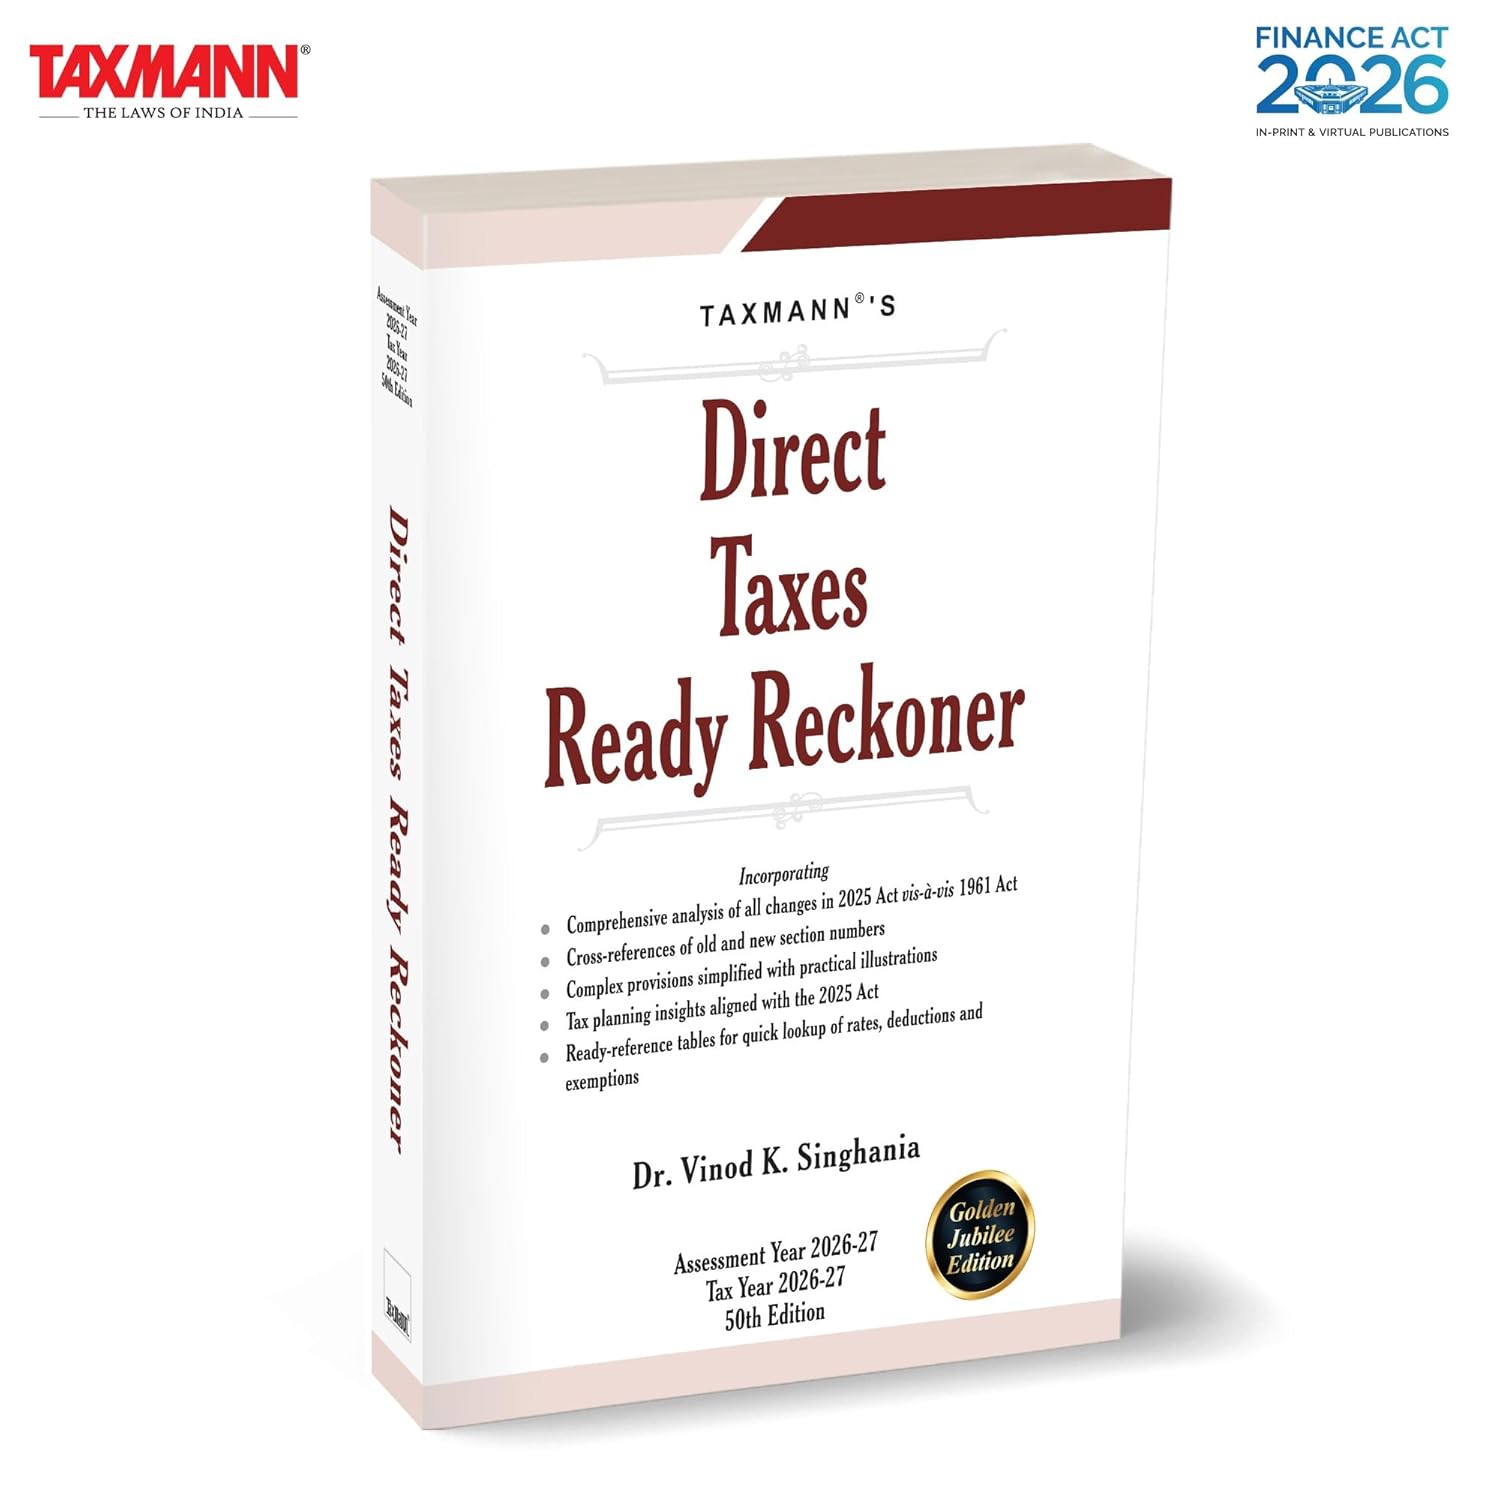
Taxmann’s Direct Taxes Ready Reckoner (DTRR) [Finance Act 2026] – India’s Most Comprehensive Reference
Direct Taxes Ready Reckoner (DTRR) is the flagship annual reference publication of Taxmann. It is the most authoritative and comprehensive single-volume guide to Indian direct tax law, updated each year.
Description
Direct Taxes Ready Reckoner (DTRR) is the flagship annual reference publication of Taxmann. It is the most authoritative and comprehensive single-volume guide to Indian direct tax law, updated each year. First published in May 1978, the 50th Golden Jubilee Edition commemorates fifty years of continuous publication under the same authorship. The DTRR 50th Edition maps, compares, cross-references, and illustrates, serving simultaneously as a practitioner’s guide, a compliance checklist, a tax calculation resource, and a manual for legislative transition. All section references default to the Income-tax Act 2025, and all rule references default to the Income-tax Rules 2026, unless explicitly indicating the 1961 Act—a deliberate editorial choice that facilitates the profession’s transition to the new legal framework.
The 50th Edition operates amid unprecedented regulatory complexity: the Income-tax Act 2025, and the Income-tax Act 1961 run concurrently—pre-2025 assessments under the old Act, new assessments under the new. The Finance Act 2026, amends both simultaneously, with differing effective dates. The Income-tax Rules 2026, further replace the 1962 Rules entirely—renumbering sections, redesignating forms, and restructuring procedural timelines across TDS, TCS, and return filing. The DTRR 50th Edition addresses all three layers in a single volume.
This book is designed for practitioners and professionals who require both depth and immediacy—those for whom accuracy is non-negotiable and lookup speed is operationally critical. The primary readership includes:
- Chartered Accountants and Tax Consultants for advisory, compliance, return filing, and tax planning mandates across all categories of assessors
- Advocates and Legal Professionals for statutory interpretation, litigation support, and penalty/interest computation
- Corporate Tax Managers and CFOs for TDS/TCS compliance, advance tax calculation, and corporate tax liability assessment
- Company Secretaries and Cost Accountants for compliance functions related to direct tax obligations
- Finance and Accounts Professionals working across industries with payroll, vendor payments, or intercompany transactions subject to withholding
- Tax Officers and Revenue Officials as quick-reference authorities on rates, limitation periods, and procedural timelines
- Academicians and Students of Advanced Taxation as comprehensive study companions integrating legislative text, practical illustrations, and case studies
The Present Publication is the 50th Edition | Golden Jubilee Edition, updated to incorporate all amendments introduced by the Finance Act 2026. Applicable for Assessment Year 2026-27 and Tax Year 2026-27, this Edition is authored by Dr Vinod K. Singhania, whose five decades of authoritative annual commentary have established this book as the definitive desk reference in Indian direct taxation. The key highlights of this Edition include:
- [Finance Act 2026—Fully Integrated] All amendments introduced by the Finance Act 2026 are incorporated directly into the relevant chapters and highlighted at the point of relevance—not relegated to a supplement. Practitioners reading any chapter see current law, not last year’s
- [Amendments at a Glance with Case Studies] Referencer 2 provides a structured three-part dissection of every legislative change—Part A covers Finance Act 2026 amendments to both the 1961 Act and the 2025 Act; Part B maps key structural changes brought in by the Income-tax Act 2025; and Part C covers procedural changes under the Income-tax Rules 2026. Each amendment is supported by practical illustrations and full numerical case studies
- [Section-wise Cross-reference Index] An exhaustive bidirectional index maps every section of the 1961 Act to its corresponding provision in the 2025 Act at the paragraph level—enabling instant location of any provision under either Act
- [New vs. Old Tax Regime—Complete Parallel Analysis] All provisions are presented in parallel for both regimes across every assessee category. For companies, four distinct tax rate regimes are fully analysed—section 199 (25% for eligible manufacturers), section 200 (22% for all domestic companies with fixed 10% surcharge and no MAT), section 201 (15% for new manufacturing companies), and section 202 (default individual/HUF new regime with restricted exemptions and deductions)
- [Salaries—Comprehensive Allowance Tables with Revised Quantum] All allowance categories are covered with AY 2026-27 quantum limits, including revised children’s education allowance (₹3,000 per month per child), hostel expenditure allowance (₹9,000 per month per child), and transport allowance for transport system employees (70% subject to ₹25,000 per month). HRA computation covers the three-limb formula with worked examples, including the reclassification of Hyderabad, Pune, Ahmedabad, and Bengaluru to the 50% metro tier from AY 2026-27
- [Presumptive Taxation—Full Treatment with 1961 Act vs. 2025 Act Comparison] All three sub-schemes under section 58 of the 2025 Act are covered with comparative illustrations. A critical difference is highlighted: under the 2025 Act, an assessee declaring income below the presumptive rate must maintain books and undergo audit if income exceeds the basic exemption limit, irrespective of prior-year history under the scheme, a departure from the more lenient position under the 1961 Act
- [Updated Return—Multi-Scenario Analysis] Covers the two key Finance Act 2026 amendments—permitting updated return filing where a declared loss is reduced, and permitting updated return filing even after a reassessment notice under section 280, subject to a graded additional tax structure of 34% to 70% depending on the timing of filing. A four-scenario tax burden comparison (voluntary disclosure, post-notice updated return, full reassessment, and immunity) is worked through with complete rupee computations
- [TDS/TCS—Exhaustive Coverage Across 100+ Provisions] Every withholding provision under section 393 of the 2025 Act is covered with its 1961 Act equivalent, applicable rates, threshold limits, surcharge and HEC overlay, and form references. Scenario-based illustrations cover salary, professional fees, works contracts, individual/HUF payments, and cross-border royalties—supported by operative CBDT circulars and landmark judicial rulings
- [Penalty Tables—Consolidated and Quantified] A comprehensive penalty reference table lists every default with the applicable section under both Acts, minimum and maximum penalties—including new obligations such as the crypto asset statement under section 409(1) (₹50,000 penalty), SFT defaults (₹1,000 per day from April 1 2026), and cash transaction violations under sections 165–167
- [Life Insurance Policy Taxation—Multi-Variable Case Studies] The four-regime taxability matrix based on policy issuance date and annual premium threshold is explained with consecutive case studies covering varying combinations of sum assured, premium quantum, and PPF contributions—including a money-back policy with staggered payouts, computed under Rule 49 of the Income-tax Rules 2026
2 reviews for Taxmann’s Direct Taxes Ready Reckoner (DTRR) [Finance Act 2026] – India’s Most Comprehensive Reference
Related products
Taxmann’s New Labour Codes – Comprehensive | Transition-ready Reference to the New Labour Codes
Taxmann’s GST Ready Reckoner [Finance Act 2026] – The Trusted Single-volume GST Reference
Taxmann’s Financial Accounting [UGCF | NEP] – Two-Volume Textbook for B.Com./B.Com. (Hons.) Students
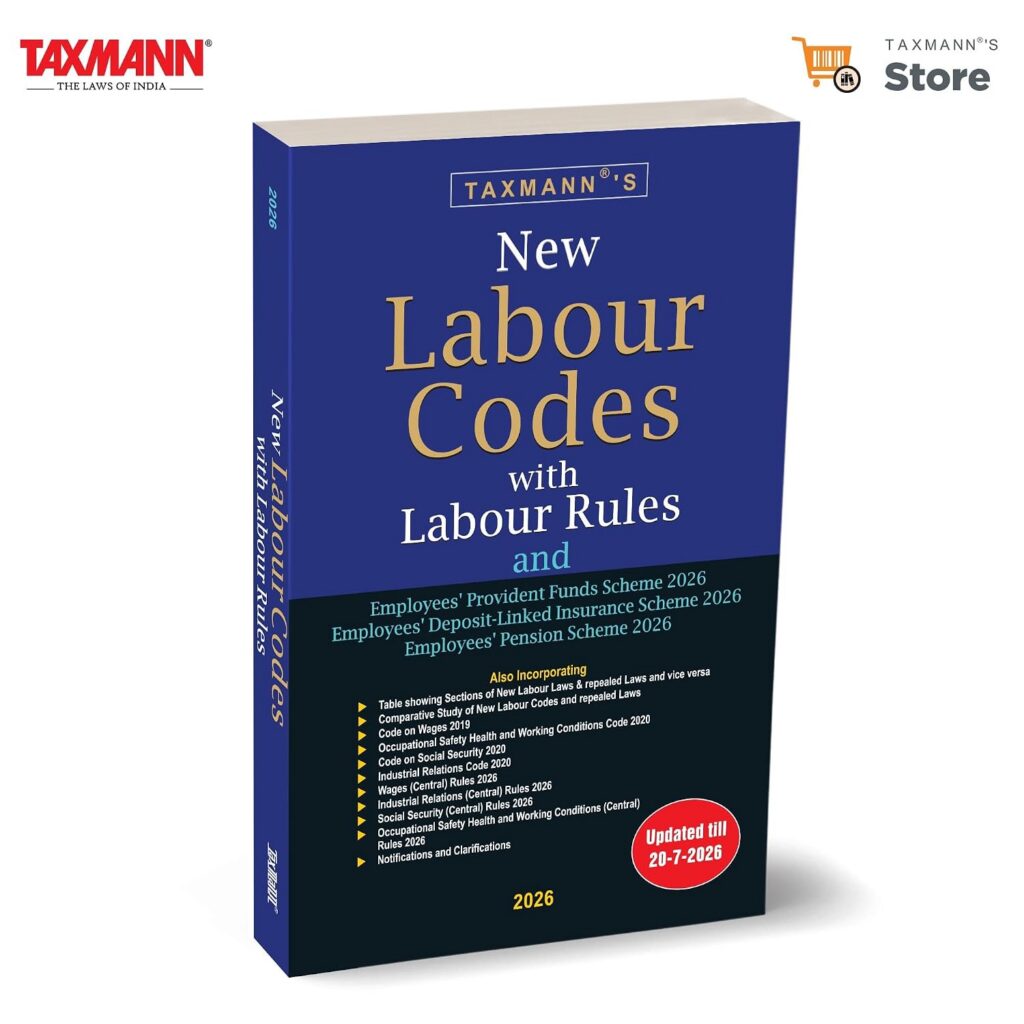
Taxmann’s New Labour Codes with Labour Rules – Single-volume Desk Companion Bringing
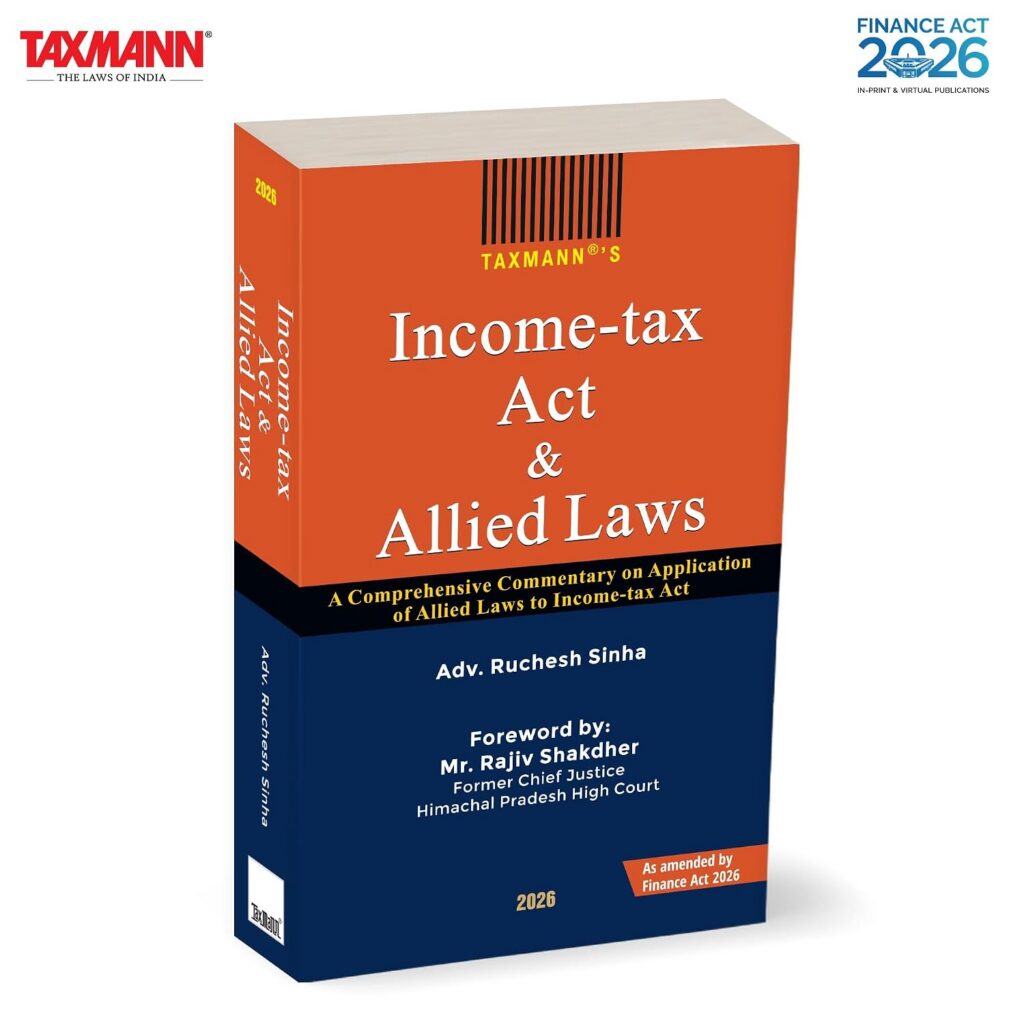
Taxmann’s Income-tax Act & Allied Laws [Finance Act 2026] – First Structured Resource To Map
admin –
Sed perspiciatis unde omnis iste natus error sit voluptatem accusantium doloremque laudantium.
admin –
Sed perspiciatis unde omnis iste natus aliquam sit voluptatem exercitationem doloremque laudantium.